
Insurance for Staffing Companies
How to Build a Program That Holds Up When a Temp Gets Hurt, a Client Sues, or Your Comp Carrier Walks
Index

Gordon B. Coyle
CEO, The Coyle Group
845-474-2924
How to get started
TL;DR. Executive Summary
The staffing owners I talk to usually call me after something has already gone wrong.
Every one of those moments is a sign that your insurance for staffing companies was built for a simpler business than the one you run today.
The Coyle Group is a commercial insurance agency that handles the complex, high-value risks other agencies don’t know how to structure, where the details in the policy are the difference between a paid claim and a denied one.
Staffing is a textbook case, because every placement puts three parties on the same claim.
Your people work inside someone else’s building, under someone else’s supervisor, and your insurance has to answer for it. You are not sure your comp will renew, whether your clients are protected when a temp gets hurt, or why general liability won’t touch a bad placement. Our approach is to build the program around how you actually place people, state by state and client by client.
In my experience, almost every program we review has at least one fatal mistake, and we find it before a claim does. The next step is a short conversation. Book a call.
What Insurance Does a Staffing Company Actually Need?
A staffing company needs a coverage stack built for being the legal employer of people who work at someone else’s site: workers’ comp with employers’ liability, general liability, staffing E&O, EPLI, cyber, and umbrella limits. But the list is the easy part. The costly mistakes hide in who requires each policy, and what the form actually says.
The scale of the risk is not small.
That industrial mix is why workers’ comp dominates your budget.
Coverage |
The staffing claim it answers |
Who requires it |
What to check in the form |
|---|---|---|---|
|
Workers’ comp + employers’ liability |
A placed worker is injured on assignment |
State law, nearly every client |
Every state you place in is listed; Part Two limits |
|
General liability |
A temp injures a third party or damages property |
Nearly every client contract |
Care, custody, or control limits; additional insured wording |
|
Staffing E&O (professional liability) |
A client says a bad placement cost them money |
Many clients, especially IT and healthcare |
Placement, screening, and breach of contract language |
|
EPLI (including third party) |
Discrimination, harassment, or wrongful termination |
Prudent; some clients |
Temps, applicants, and client-employee claims |
|
Cyber |
Breach of applicant SSNs, bank details, payroll data |
Increasingly in client contracts |
Notification, forensics, and funds transfer sublimits |
|
Umbrella or excess |
A claim that blows through your primary limits |
Client contracts |
Follows form over employers’ liability and auto |
|
Crime (with client property) |
A temp steals from a client |
Retail, logistics, and event clients |
Third-party or client property coverage |
|
Hired and non-owned auto |
A recruiter or temp crashes on company business |
Prudent |
Who is driving, and whose vehicle |
|
An error administering benefits |
Prudent |
Usually an endorsement to EPLI or GL |
|
|
Medical professional liability |
A placed nurse or clinician makes a clinical error |
Healthcare clients |
Per-claim and aggregate limits |
Contact us if you want this table filled in against your current policies.
Why Doesn’t a Standard Business Policy Fit a Staffing Firm?
A standard business policy doesn’t fit because it assumes your employees work in your space, under your control. Staffing breaks that assumption on every placement. And here is the part that surprises owners: regulators and courts don’t let you hand the responsibility off to the client just because the client runs the worksite.
OSHA states plainly that the staffing agency and its client are joint employers of temporary workers, and both are responsible for keeping those workers safe. Under OSHA’s Multi-Employer Citation Policy (CPL 02-00-124), more than one employer can be cited for the same hazard, based on whether it created, exposed, corrected, or controlled it.
Your firm can be the “exposing” employer even when the client built the unsafe scaffold.
That is why I use what I call The Three-Party Test before looking at any staffing program.
Every placement has to answer three questions, and each answer points to a coverage:
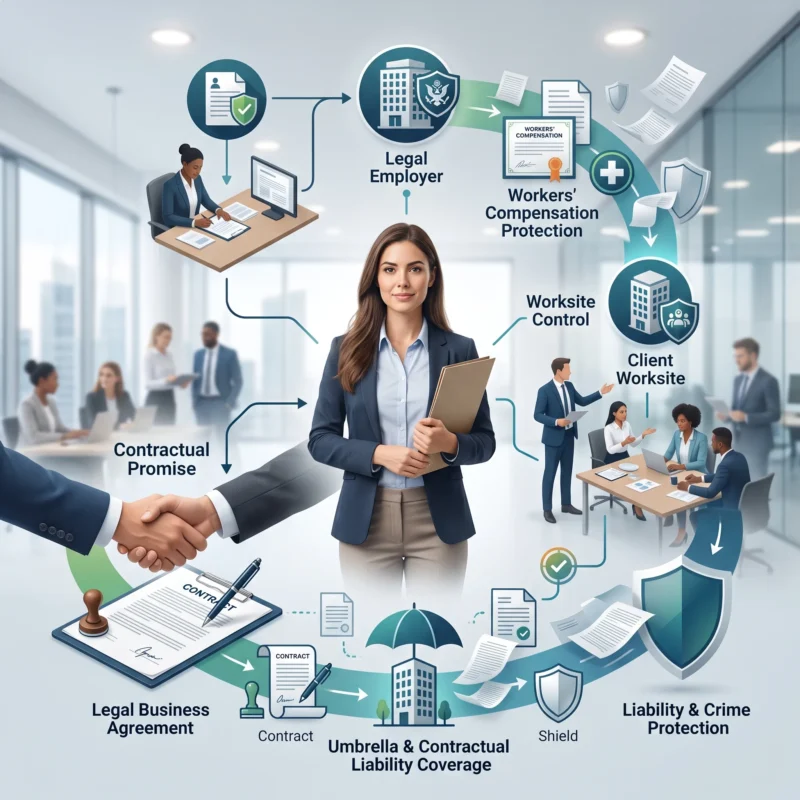
If any answer doesn’t match a policy, you have found a gap in your insurance for staffing companies.
Book a call to run the Three-Party Test on your top five clients.
How Does Workers’ Comp Work When Your People Work at a Client’s Site?
Your workers’ comp policy covers your placed workers wherever they work, including at a client’s facility, and that is usually the first question owners ask. But covering the worker is only half the job. If the endorsements are wrong, your client can still be sued directly, and that lawsuit lands back on your relationship.
Here is how the pieces fit together:
A common mistake is assuming additional insured status covers this. It doesn’t.
In most states, you cannot add a client as an additional insured on a comp policy.
Placing Workers in More Than One State
Multi-state firms carry a second layer of risk. Workers’ comp is required in nearly every state, with Texas the well-known exception where coverage is elective.
For the full picture on rating, classes, and state rules, see our workers’ compensation insurance guide.
Which Policy Responds When a Placed Worker Causes a Loss?
The policy that responds depends on what kind of loss the placed worker caused: bodily injury goes to general liability, financial loss from a bad placement goes to staffing E&O, theft goes to crime, and harassment goes to EPLI. The trouble starts when a claim falls between two policies, and each carrier points at the other.
This table covers the claims I see most often when we review insurance for staffing companies:
Scenario |
Policy that should respond |
The gap that bites |
|---|---|---|
|
Temp is injured at a client site |
Workers’ comp + alternate employer endorsement |
Client sued directly if the endorsement is missing |
|
Temp damages a client’s equipment |
General liability |
Care, custody, or control limits on property the temp was using |
|
Temp drives to a job and causes a crash |
Hired and non-owned auto, or commercial auto |
Personal auto policy excludes the business use |
|
Temp steals from the client |
Crime with client property coverage |
Standard crime only covers your own money |
|
Client says a bad placement cost them revenue |
Staffing E&O |
General liability excludes pure financial loss |
|
Temp is harassed by a client supervisor |
EPLI, including third-party coverage |
Policy written only for your internal staff |
|
Hacker steals applicant SSNs and bank details |
Cyber |
Two lines deserve extra attention.
First, staffing E&O.
A client suing because a placed worker misrepresented credentials or botched their work is a professional liability claim, and general liability won’t answer it. Good staffing forms can add breach of contract, vicarious liability for placed personnel, and loss of fees.
Our guide to when you need professional liability (E&O) explains how these policies work.
Second, EPLI.
Make sure your employment practices liability covers applicants and placed workers, and add third-party EPLI for claims involving client employees.
Talk to us if you are not sure which policy would answer your last incident.
What Do Client Contracts Require, and How Do You Prove It Fast?
Client contracts usually require specific limits, additional insured status, a waiver of subrogation, an alternate employer endorsement, and a certificate of insurance before a worker starts. The list is not the hard part. The indemnity clause buried three pages later is, because it can promise more than your policies will pay.
The typical asks look like this:
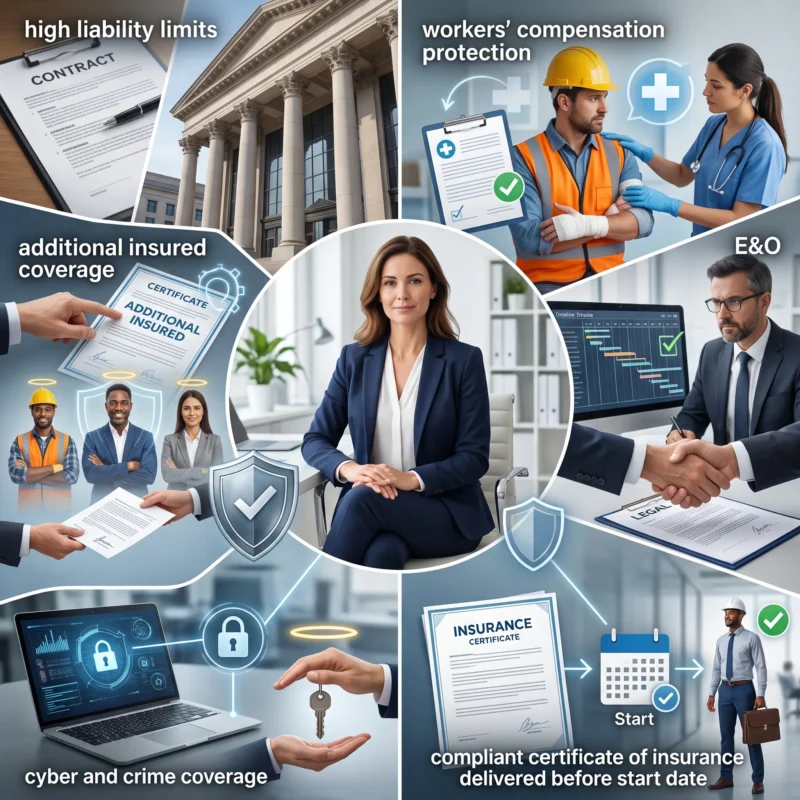
A certificate of insurance proves coverage exists. It does not prove the endorsement language matches the contract, so savvy clients now ask for the endorsements themselves. Then look at the indemnity section.
When a service agreement makes you responsible for the client’s own negligence, you have taken on contractual liability that your policies may not fully cover.
Our guides to risk transfer and indemnity agreements and customer contract insurance requirements walk through what to push back on.
Size your limits with a clear view of commercial umbrella vs. excess liability, because the wrong structure can leave employers’ liability or auto uncovered above the primary.
Should You Carry Your Own Program or Use a PEO or Employer of Record?
Carry your own program when you want control over coverage, claims, and cost, and your payroll and loss history can earn good terms. A PEO or employer of record can suit younger or harder-to-place firms. But almost every page pushing that option comes from a company selling it, so look hard at the tradeoffs first.
Structure |
Who carries comp and liability |
Control and cost clarity |
Best fit |
Watch out for |
|---|---|---|---|---|
|
Guaranteed-cost program (your own) |
You, through your broker |
High |
Most established firms |
Audit swings if class codes drift |
|
You, with a retained layer |
Highest, with rewards for good loss history |
Larger firms with strong safety results |
Collateral and claims-handling demands |
|
|
Specialty staffing program |
You, through a program administrator |
Moderate |
Hard-to-place classes or mixed industries |
Narrow appetite, frequent underwriting changes |
|
PEO (co-employment) |
Shared with the PEO’s master policies |
Lower |
Small firms needing access to comp |
Retentions, pooled pricing, limited say in claims |
|
Employer of record |
The EOR, as legal employer |
Lowest |
New firms or new states |
You still need your own corporate coverage |
The PEO watch-out is one I raise with owners all the time.
Many owners never read that clause until a claim arrives. An employer of record can take on the employment-side policies, but it does not insure your own recruiters, your office, your data, or your professional mistakes.
You still need corporate general liability, E&O, and cyber insurance in your own name.
As firms grow, most of the ones I work with move their insurance for staffing companies into a program of their own, which is the same shift we see across mid-market business insurance.
Book a call to compare your current structure against a program of your own.
What Does a Staffing Insurance Problem Look Like in Real Life?
A staffing insurance problem usually looks like a paperwork detail that turns into a five- or six-figure bill. It rarely starts with a catastrophe. It starts with a class code, a missing endorsement, or a contract nobody reviewed, and it surfaces at audit or claim time, when it is too late to fix cheaply.
Real example (the class code the client picked):
A California staffing company received a workers’ comp audit bill of more than $80,000 from its carrier, along with a cancellation notice that would take effect if the bill was not paid within ten days. When a workers’ comp consultant asked why the firm had reported its payroll under the class code it used, the owner explained it was the code the client told them to use. The payroll belonged in a different classification, and the audit priced it that way retroactively. The lesson: your class codes are your responsibility, not your client’s, and they have to match the actual work at each site.
The risk profile also changes with what you place:
Contact us to check your codes before your next audit does.
How Much Does Insurance for Staffing Companies Cost, and What Drives It?
The cost of insurance for staffing companies depends mostly on workers’ comp, which is priced per $100 of payroll by class code, state, and experience mod. Estimates run from under $1 per $100 for clerical codes to over $10 for industrial ones. But the rate you are quoted is not the final bill. The audit decides what you actually pay.
Line |
How it is priced |
What pushes it up |
What you control |
|---|---|---|---|
|
Workers’ comp |
Per $100 of payroll by class code and state |
Industrial codes, claims, a high experience mod |
Correct codes by job and site, safety programs, claims management |
|
General liability |
Revenue or payroll, by class |
Heavy industrial placements, claims |
Contract review, worksite screening |
|
Staffing E&O |
Revenue and placement type |
IT and healthcare placements, high limits |
Screening and credential checks |
|
EPLI |
Headcount and claim history |
Turnover, prior charges |
HR practices, documented terminations |
|
Cyber |
Records held, security controls |
Weak controls, large applicant databases |
Multifactor authentication, data retention limits |
|
Umbrella |
Underlying limits and class mix |
Industrial exposure, auto |
Right-sized primary limits |
Why Your Audit Bill Is the Real Price
Your comp premium starts as an estimate. At audit, the carrier looks at actual payroll, and every dollar lands in a class code.
Three things cause most of the ugly surprises I see:
How Your Experience Mod Follows You
Your experience modification factor compares your claims to similar firms. One bad year can lift your mod for three years, and a high mod shrinks the list of carriers willing to quote you.
In 2026, I am also seeing carriers tighten their appetite for staffing classes, restructure programs, and send non-renewals to firms that did nothing wrong except place workers in industrial jobs.
The cheapest quote is rarely the cheapest program.
The price that matters is what you pay after the audit and after the first serious claim.
How Do You Know If Your Broker Really Understands Staffing?
You know your broker understands staffing when they talk about class codes, experience mods, endorsements, and your client contracts before they talk about price. A generalist quotes a premium. A specialist asks where your people work. And the difference usually shows up at the worst possible moment: the week your carrier sends a non-renewal.
“Bottom line is that almost all insurance programs we review contain at least one fatal mistake.”
With staffing firms, it is usually a code, an endorsement, or a contract clause.
Judge your current broker against this checklist:
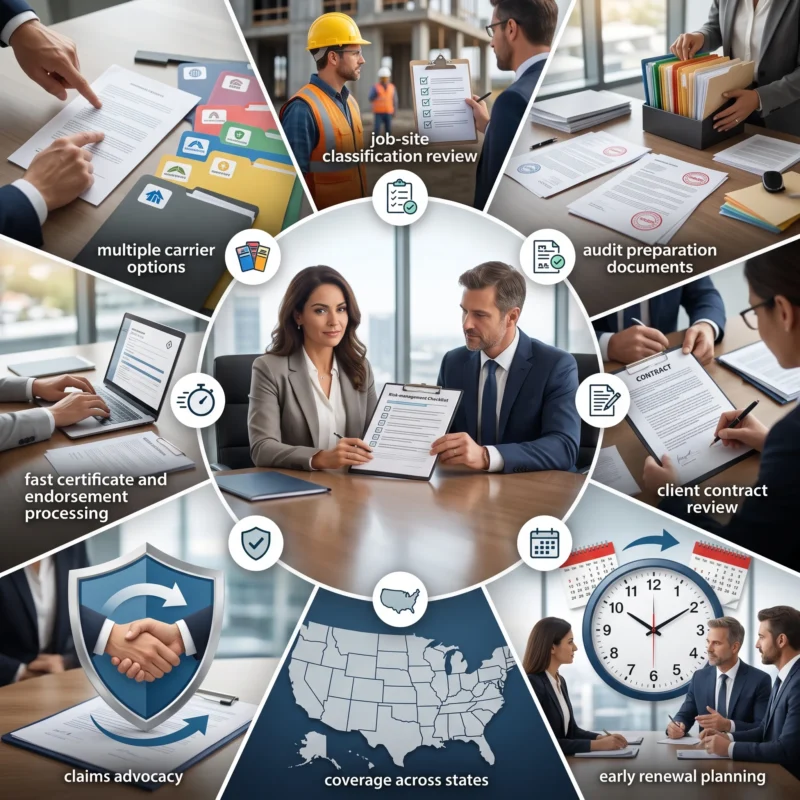
If you checked fewer than six, it may be time to ask should you switch insurance brokers.
Many firms find that their insurance broker has outgrown them after a merger or a staff change.
Not ready to switch? Get a second opinion on your business insurance first.
Work With a Broker Who Insures the Way You Actually Place People
The right insurance for staffing companies is not a bigger policy. It is a program that passes the Three-Party Test on every placement, survives an audit, and meets your toughest client contract. I have spent over 40 years helping business owners find the gaps before the gaps find them, and staffing is where those gaps hide in the smallest details.
If your comp renewal is coming up, a client contract just landed on your desk, or your last audit hurt, let’s talk about what your program actually covers.
You can also browse our other insurance by industry guides.
Book a call and we will start with a no-obligation review.
Questions about Insurance For Staffing Companies?
Get the Right Coverage for Your insurance for staffing companies
In staffing, your people work under someone else’s roof, and your policies answer for it. In my experience, the costly problems start small: a wrong class code, a missing endorsement, or a contract clause nobody read.
We build your program around how you actually place people. That means checking your codes by job and site, getting you ready for audits, and turning around certificates fast. We also review your client contracts and start renewals early.
If a renewal, a new contract, or your last audit has you worried, let’s talk. We’ll start with a no-obligation review of what your program covers, and what it doesn’t.

This article was written by the CEO of The Coyle Group, Gordon B. Coyle, CPCU, ARM, AMIM, PWCA, who has over 40 years of experience working with business owners of all sizes and industries across the US, solving their insurance challenges.
Here’s how to take the next step
Schedule Your Insurance Confidence Assessment
In our 30-minute call, you’ll discover:
Not ready for a call?
Get Free Access to Our Gated Video:
“How to Finally Feel Confident in Your Coverage. “
And discover the exact system we use to help business owners eliminate hidden coverage gaps, stop overpaying, and finally feel confident in their protection.
What Peace of Mind Looks Like
Trusted by business owners across the U.S.
The Coyle Group is 1st class! Gordon and his team are knowledgeable, responsive, and attentive to detail. Gordon is that rare breed of professional who genuinely cares for his clients and works hard to exceed their expectations. I highly recommend them.


The insurance brokerage service was truly tailored to my needs, nothing like those big brokers who steer you toward random policies that don’t fit your profile. Thank you to the team for your help.

I was working with another broker and having difficulty acquiring General Liability coverage. A colleague recommended The Coyle Group. They were able to get coverage bound in just a couple of business days and a policy issued in ten days, and with a solid carrier at a competitive premium. Truly impressive results, plus it was a pleasure working with them. I highly recommend the Coyle Group!

If any business is looking to work with an insurance brokerage firm that is not only excellent at what the firm does, but one that deeply values the needs of the clients, then The Coyle Group is the firm for you. Give them a call and see for yourself. I can assure that you will quickly agree.

Want to know more?
See related blogs

The Crowdstrike Debacle and Cyber Insurance
Third Party Employment Practices Liability Insurance. Protect Your Business

Are You Overpaying or Underinsured on Your Business Insurance?
