Leaving a PEO (professional employer organization)
The Insurance Checklist to Exit Without a Coverage Gap
Index

Gordon B. Coyle
CEO, The Coyle Group
845-474-2924
How to get started
TL;DR. Executive Summary
Most owners I talk to describe the same moment. They decided months ago that the PEO had to go, and then they found the hidden trap at the exit door.
The notice window had already passed.
The benefits renewal came in at 25% when everyone budgeted for single digits.
And when they called a carrier about workers’ comp, the underwriter treated them like a brand-new business with no track record, even after ten clean years. Leaving a PEO is not just a payroll project.
The PEO (professional employer organization) was quietly running your insurance program, and the day you leave, that program ends.
The Coyle Group is a commercial insurance agency that handles the complex, high-value risks other agencies don’t know how to structure, where the details in the policy are the difference between a paid claim and a denied one.
A PEO exit is one of those moments, because every master policy you relied on stops on the same day.
You want out of the PEO, but you are not sure what coverage you actually have, what disappears on your exit date, or whether a carrier will write you on your own. Our approach is to map every PEO policy to its replacement before you send notice, so workers’ comp, EPLI, and benefits start the minute the PEO’s coverage ends. We do this work confidentially, and it does not disrupt any relationship you have today.
The next step is a short conversation. Book a call.
This guide to leaving a PEO is for established companies, usually 25 employees or more, with a real payroll, a real benefits budget, and customer contracts to honor.
If you are still a team of a handful, a PEO may well be the right fit for now.
What Happens When You Leave a PEO?
When you leave a PEO, every policy it carried for your employees ends on your exit date, and you become the sole employer under your own tax ID. Most owners expect that part. What catches them off guard is how much coverage the PEO was holding that they never saw, and how little of it follows them out.
Inside a PEO, you share employer duties through co-employment. The PEO runs payroll under its tax ID and covers your people under its own master policies.
When you leave, your employees keep their jobs, their pay, and their managers. What changes is who sponsors their coverage. They become your employees alone, they receive new enrollment materials, and their health plan, workers’ comp, and retirement plan all get rebuilt in your name.
I call the tool below the PEO Exit Coverage Map.
It is the first thing we build for any owner who is serious about leaving a PEO.
Coverage |
Inside the PEO |
The day after you leave |
What to have ready |
|---|---|---|---|
|
Workers’ comp |
The PEO’s master policy |
Ends, with no grace period |
Your own policy, bound to start the same minute |
|
EPLI |
The PEO’s group policy, often with a high retention |
Ends with your service agreement |
Standalone EPLI with prior acts or a retro date that reaches back |
|
Health, dental, vision |
The PEO’s master plan |
Ends on the termination date |
A new group, level-funded, or ICHRA plan with a matching start date |
|
401(k) |
Often a pooled or multiple-employer plan |
Your share has to be unwound |
Your own plan, an ERISA fidelity bond, and fiduciary liability |
|
COBRA, FSA, leave admin |
Run by the PEO |
Your responsibility |
A COBRA administrator and a plan for FSA balances |
|
Cyber and crime |
Rarely included |
Never existed |
Policies sized to your data and money flows |
|
General liability, auto, property |
Usually bought separately |
Must match your entity and payroll |
Updated exposures and classifications |
The cost of leaving a PEO without a plan is concrete:
Why Do Companies Leave a PEO?
Companies leave a PEO because they outgrow it. Costs outpace headcount, renewals arrive as a number instead of a conversation, and claims data stays locked away. The reasons to leave a PEO rarely come down to one bad month. Still, the reason you leave shapes what you need to build next, so name it first.
These are the reasons I hear most often:
Benefits consultants often put the break-even point for leaving a PEO somewhere between 50 and 150 employees, depending on location and workforce.
Below that range, the PEO’s pooled buying power can still win. Above it, a program of your own usually earns better terms. You are far from alone in reaching that point.
NAPEO reports that at the end of 2025, 502 PEOs served 233,000 client businesses and 5.4 million worksite employees.
Plenty of companies end up leaving a PEO every year, and the ones that do it well treat the move like any other major mid-market business insurance decision.
Not sure whether you have outgrown yours? Contact us and we will talk through the numbers with you.
Does Leaving a PEO Affect Your Workers’ Comp Insurance?
Yes. Leaving a PEO ends your workers’ comp on your exit date, because the PEO owns the master policy and you cannot take it with you. That alone is manageable. However, the bigger surprise is what happens to your claims history, because that history decides what carriers charge you for years.
I like to start workers’ compensation underwriting 90 to 120 days before the exit date.
That window gives us time to gather data, fix class codes, and get terms from more than one carrier before the PEO’s coverage stops.
Usually the PEO’s carrier keeps claims from its policy period, but you want that confirmed, not assumed.
Business owners tell me standard carriers can hesitate when an account is leaving a PEO.
That is not a reason to stay.
It is a reason to present your account well, with clean data and a real safety story.
For manufacturers, where comp is often the biggest line, this step matters even more.
Your experience mod compares your claims to similar businesses.
A 1.00 is average, a lower number earns a credit, and a higher one costs you more.
Inside a PEO master policy, the PEO may have reported your claims under its tax ID instead of yours.
As a result, you may come out with an accurate mod, a “new business” 1.00, or murky data that works against you. NCCI has a reporting process for a client’s experience when that client leaves a PEO master policy, and you want proof it happened.
Carriers won’t price you without loss runs.
Ask the PEO for five years of loss history for your company, under your FEIN, with payroll by class code.
Ask before you give notice.
Does Your PEO‘s EPLI Follow You Out the Door?
Usually not. Most PEO EPLI covers you only while you remain a client, and it typically ends with your service agreement, often with no tail and no prior acts coverage. That sounds like fine print. In practice, though, a lawsuit over a firing from last year can land on nobody’s policy.
EPLI is almost always written on a claims-made basis.
The policy that responds is the one in force when the employee makes the claim, not the one in force when the firing happened.
If you want a refresher, here is how tail coverage works in a claims-made policy.
When you are leaving a PEO, that structure creates four problems:
Switching from one PEO to another makes this worse, because continuity resets with every new service agreement.
If you are unsure where EPLI stops and management liability starts, compare D&O vs. EPLI before you buy.
Real-world example (two PEOs, zero continuity)
An 80-employee company carried standalone EPLI for six years, then cancelled it when it joined a PEO and bought an extended reporting period that later expired. The PEO’s EPLI covered only co-employed workers, with no retroactive coverage and no tail. A couple of years later, the company moved to a second PEO with the same terms. When it finally went looking for its own policy, it had terminated 13 employees over that stretch, 1099 contractors had never been covered, and five carriers declined to fill the gap. No one had filed a claim yet, but the company could not buy the protection it assumed it had. Keeping standalone EPLI, or excess coverage over the PEO’s, with continuous prior acts would have prevented all of it.
Before you send notice, let us read your PEO’s EPLI and workers’ comp terms. The review is confidential, and it does not disrupt your current relationships. Book a call.
What Coverage Did Your PEO Never Give You?
Most PEOs never gave you cyber, crime, or fiduciary coverage, even if you assumed the bundle included them. Those exposures existed the whole time. Yet leaving a PEO is the moment they become impossible to ignore, because you now own the payroll, the data, and the retirement plan.
From what I’ve seen, owners leaving a PEO spend months choosing a payroll platform and minutes on these lines.
That is backwards.
Can You Leave a PEO Mid-Year?
Yes, you can leave a PEO mid-year, but a year-end exit is cleaner and usually cheaper. A mid-year move creates two W-2s, can restart payroll tax wage bases, and interrupts benefit plan years. Still, whether it costs you thousands depends on one detail most owners never check: whether your PEO is certified by the IRS.
When you leave a non-certified PEO mid-year, your employees become new hires under your own tax ID, and some wage bases restart.
A certified PEO (CPEO) works differently.
The IRS explains how CPEO customers are treated for federal employment taxes, and you can check your provider against the IRS list of certified PEOs. State unemployment rules vary, so confirm the details with your CPA.
Year-end exit |
Mid-year, non-certified PEO |
Mid-year, certified PEO |
|
|---|---|---|---|
|
W-2s for employees |
One |
Two |
Usually two |
|
Social Security and FUTA wage bases |
Reset with the calendar |
Can restart under your EIN |
Generally carry over |
|
State unemployment |
Resets with the calendar |
Often restarts |
Depends on the state |
|
Deductibles and plan year |
Clean |
Employees may lose progress |
Employees may lose progress |
Here is the worked example for leaving a PEO mid-year that I promised earlier.
Take one employee earning $300,000 who leaves the PEO with you on July 1, after $150,000 in wages:
Employees under the cap see no Social Security double-up. FUTA and state unemployment bases, however, can restart for everyone. Can you leave before your contract ends? Usually, yes, at a price.
Most agreements require 30 to 90 days of written notice, some auto-renew if you miss a window, and some charge an early termination fee.
Read the termination clause before you commit to leaving a PEO.
Want a second set of eyes on your timing? Start with a second opinion on your business insurance.
Your Leaving a PEO Checklist: How to Leave a PEO Without a Gap
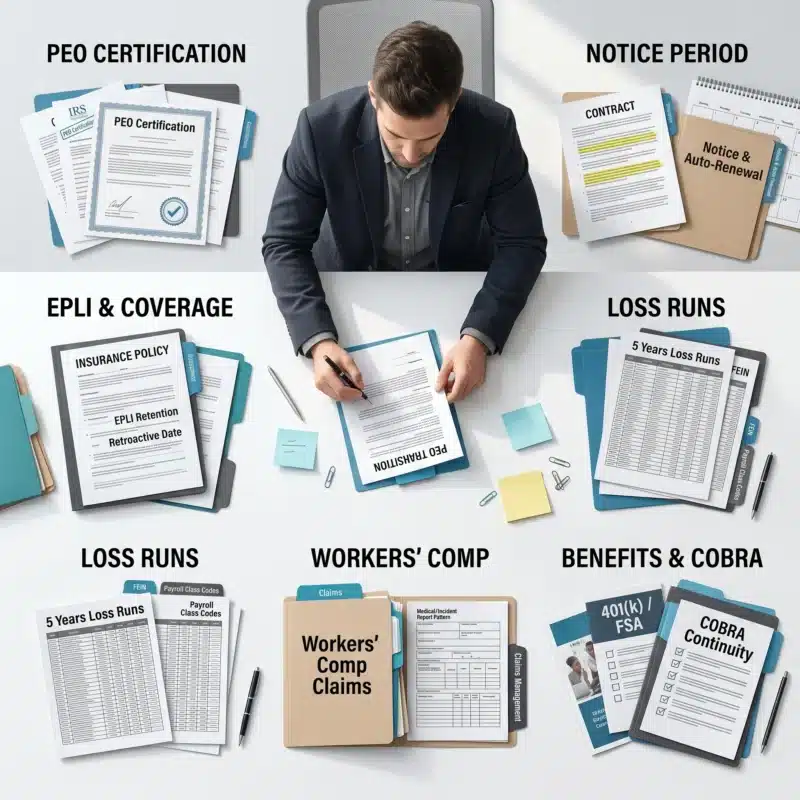
The cleanest way to leave a PEO is to work backward from your exit date, start six months out, and finish the insurance before payroll. A good leaving a PEO checklist makes every coverage start the minute the old one ends. The step most owners skip is requesting data before notice, and that step costs the most later.
When |
Insurance |
Payroll, benefits, and HR |
|---|---|---|
|
6+ months out |
Pull the PEO agreement, master policy terms, and EPLI retention. Request five years of loss runs and claims history |
Read the termination clause and auto-renewal date. Choose one benefits and insurance broker |
|
4 to 6 months out |
Submit workers’ comp and EPLI to carriers. Price cyber, crime, and fiduciary |
Request census, payroll history, PTO balances, and deductible accumulator data. Pick a payroll and HRIS platform |
|
2 to 3 months out |
Bind terms with start dates that match the exit date |
Send written notice. Register state tax accounts. Set up COBRA and leave administration |
|
30 to 60 days out |
Issue new certificates of insurance to customers and landlords |
Run open enrollment. Tell employees what changes and what stays the same |
|
Exit day and after |
Confirm every policy is in force and who handles open claims |
Run the first payroll under your EIN. Reconcile first invoices line by line |
Transition Payroll Without Disrupting Anyone
Protect Your Employees’ Benefits
No two plans for leaving a PEO look exactly alike. If you want help building this timeline around your renewal dates, contact us.
What Does It Really Cost to Leave a PEO?
The real cost of leaving a PEO equals your new all-in spend minus your old all-in spend, not the PEO invoice minus a benefits quote. Many companies still come out ahead. But the services the PEO bundled come back one line at a time, and the insurance lines are the ones owners forget to price.
Inside the PEO (all-in) |
After you leave (all-in) |
|---|---|
|
PEO admin fee (percentage of payroll or per employee) |
Payroll and HRIS, often $5,000 to $25,000+ to implement, plus $5 to $25+ per employee per month |
|
Benefits premiums |
Your own group, level-funded, or ICHRA premiums |
|
Bundled workers’ comp |
Standalone workers’ comp priced on your class codes and mod |
|
Bundled EPLI, often with a high retention |
Standalone EPLI with prior acts |
|
COBRA and compliance tools |
A COBRA administrator and ACA reporting |
|
Usually not included |
Cyber, crime, fiduciary, and an ERISA bond |
|
Not applicable |
Any termination fee, plus wage-base restart costs if you leave mid-year |
I never promise that leaving a PEO saves money. What I can tell you is that the cost of leaving a PEO looks very different once you price every line.
Meanwhile, the losses come from skipping the lines above and finding out after a claim. Price is also where owners fall into what I call the cheap policy trap.
A standalone EPLI quote with a narrow retro date will always look cheaper than one with full prior acts. It is cheaper because it covers less.
What Should You Think About Before Leaving a PEO?
Before leaving a PEO, think about three things: what your contract allows, what your PEO’s policies actually cover, and who will rebuild your program. The contract question is easy to answer. The coverage question is not, and the answers usually live in documents the PEO never sent you.
Ask your PEO these questions, in writing:
A clear answer to both is a good sign. You can compare their answer with what your insurance broker should be doing for an account like yours.
What Are the Best Alternatives to Your PEO?
For most growing companies, the best solution for leaving a PEO is a payroll platform of your own plus one broker who builds your benefits and insurance program. It is not the only path. However, each option changes your insurance differently, and a PEO-to-PEO switch can reset your EPLI continuity all over again.
Path |
Who carries comp and EPLI |
Your control |
Best fit |
Watch out for |
|---|---|---|---|---|
|
Stay and renegotiate |
The PEO |
Low |
Smaller teams the PEO still prices well |
The same data and control limits |
|
Switch to another PEO |
The new PEO |
Low |
Companies that still want bundling |
EPLI continuity resets |
|
ASO or benefits carve-out |
You, or a mix |
Medium |
Teams that want admin help but their own plans |
Clarify who sponsors each policy |
|
Traditional payroll plus your own program |
You, through your broker |
High |
Most companies past 50 employees |
You own compliance, so staff for it |
The PEO vs. traditional payroll comparison confuses a lot of owners. A payroll provider runs pay and tax filings under your EIN, but it does not co-employ your people, so it carries none of your insurance.
You buy that coverage directly. One more point on choosing help. You don’t need five brokers shopping your insurance.
You need one capable broker making sure the right insurers compete for your business. Sending the same census to several brokers confuses underwriters and can block markets.
If you need to make a change, here is how to switch insurance brokers without a gap.
How We Review the Insurance Side of a PEO Exit
We review the insurance side of a PEO exit before you give notice, so you know exactly what you are leaving and what you need on day one. It starts with a short, confidential conversation. Then the real work happens in the documents, which is where most exit surprises hide.
Here is what our Confidential Review covers when you are leaving a PEO:
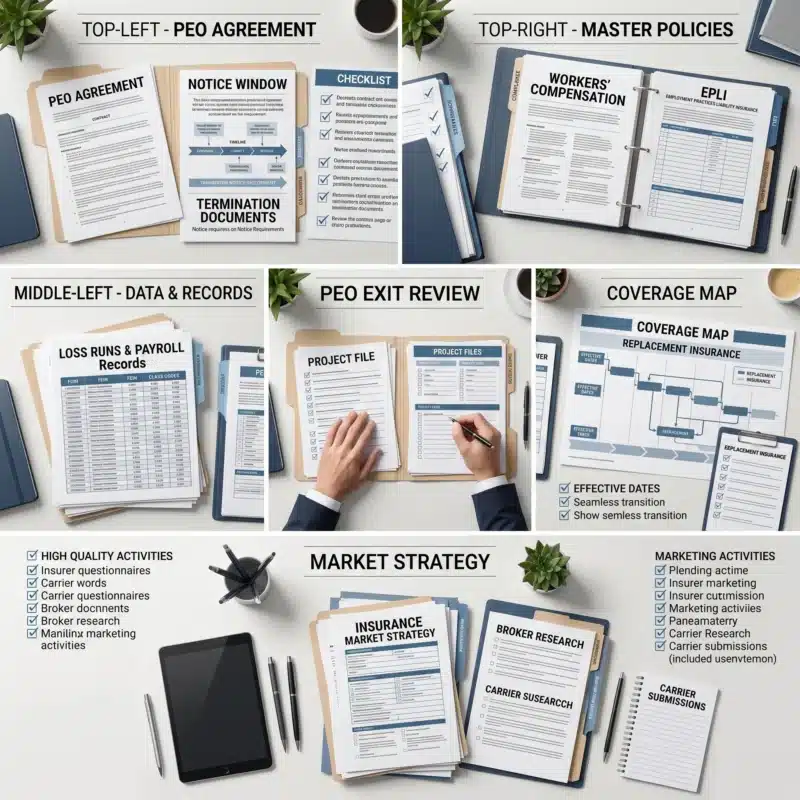
If you already have coverage outside the PEO, we review it first.
If you are buying everything new, we build the underwriting picture before we approach a single carrier.
Either way, we keep the work confidential, and it does not disrupt your PEO or any broker relationship until you decide.
Leave Your PEO With Your Coverage Intact
A successful plan for leaving a PEO is not the one with the lowest first-year bill. It is the one where every policy starts the minute the old one ends, and your claims history comes with you. Over 40 years, I’ve watched owners get this right when they planned the insurance first and the payroll second.
If your PEO renewal is coming up, or you have already decided to leave, let’s look at what your program really covers today.
You can find more practical guidance in our insurance advice for business owners.
When you are ready, book a call and we will start with a no-obligation review.
Questions about Leaving A Peo?
Get the Right Coverage for Your leaving a PEO
When you’re leaving a PEO, you don’t need another stack of quotes. You need someone to make sure the program you’re stepping into is built right. My job isn’t to get you an insurance quote. My job is to make sure your insurance is right. That means reading the PEO’s master policies, finding what ends on your exit date, and rebuilding workers’ comp, EPLI, and everything the PEO never covered, so it all starts the minute the old coverage stops.
I’ve been reviewing business insurance programs for years, and The Coyle Group has served business owners since 1929. We’re an independent commercial insurance brokerage, and business insurance is all we do, for companies across the US. We have access to many insurance markets, but we don’t spread your account across five brokers and hope the price comes out right. We look at your loss runs, your class codes, your retro dates, and your contracts first. Then we bring your account to the insurers that actually fit it, and we tell you why we chose them.
If you’re planning your exit, start with a confidential review of what you have today. It’s a short conversation, not an application, and it doesn’t disrupt your PEO or any other relationship until you decide. You’ll come away knowing exactly what your program covers, where the gaps are, and what it takes to leave with nothing left exposed.
This article was written by the CEO of The Coyle Group, Gordon B. Coyle, CPCU, ARM, AMIM, PWCA, who has over 40 years of experience working with business owners of all sizes and industries across the US, solving their insurance challenges.
Here’s how to take the next step
Schedule Your Insurance Confidence Assessment
In our 30-minute call, you’ll discover:
Not ready for a call?
Get Free Access to Our Gated Video:
“How to Finally Feel Confident in Your Coverage. “
And discover the exact system we use to help business owners eliminate hidden coverage gaps, stop overpaying, and finally feel confident in their protection.
What Peace of Mind Looks Like
Trusted by business owners across the U.S.
The Coyle Group is 1st class! Gordon and his team are knowledgeable, responsive, and attentive to detail. Gordon is that rare breed of professional who genuinely cares for his clients and works hard to exceed their expectations. I highly recommend them.

The insurance brokerage service was truly tailored to my needs, nothing like those big brokers who steer you toward random policies that don’t fit your profile. Thank you to the team for your help.
I was working with another broker and having difficulty acquiring General Liability coverage. A colleague recommended The Coyle Group. They were able to get coverage bound in just a couple of business days and a policy issued in ten days, and with a solid carrier at a competitive premium. Truly impressive results, plus it was a pleasure working with them. I highly recommend the Coyle Group!
If any business is looking to work with an insurance brokerage firm that is not only excellent at what the firm does, but one that deeply values the needs of the clients, then The Coyle Group is the firm for you. Give them a call and see for yourself. I can assure that you will quickly agree.

Want to know more?
See related blogs

The Crowdstrike Debacle and Cyber Insurance
Third Party Employment Practices Liability Insurance. Protect Your Business

Are You Overpaying or Underinsured on Your Business Insurance?
