
Insurance for Marketing Agencies
What Pays When a Client Sues You (and What Won’t)
Index

Gordon B. Coyle
CEO, The Coyle Group
845-474-2924
How to get started
TL;DR. executive Summary
Good insurance for marketing agencies starts with professional liability (E&O) that includes media liability, plus cyber, general liability, property, workers’ compensation, and EPLI, then D&O and umbrella as the agency grows. General liability and a BOP will not answer most client claims. Cyber exposure follows your access to client platforms, not whether you store card data. Client contracts set your minimum limits, not your right limits. And because E&O is claims-made, a lapse or a careless carrier switch can erase coverage for years of past work.
Or a campaign runs hot over a long weekend, there is “nothing in the contract about overage,” and the client’s card is attached to every ad platform.
That is usually the moment an owner starts looking hard at insurance for marketing agencies, and it is the worst possible moment to learn what your current policy actually does.
In my experience, the agencies that get hurt are not careless.
The Coyle Group is a commercial insurance agency that handles the complex, high-value risks other agencies don’t know how to structure, where the details in the policy are the difference between a paid claim and a denied one.
You are in the right place if
You run an agency with real client contracts, real payroll, and real media budgets under management, and you are not sure your coverage would respond if a client blamed you for a campaign, a piece of content, or a breach. When we review a program, we find at least one fatal mistake nine times out of ten.
Book a call and I will tell you straight where yours is.
Insurance for marketing agencies: what coverage do you actually need?
Most established agencies need six to eight coordinated policies, anchored by professional liability (E&O) with media liability, cyber, and general liability. However, the policy most agencies bought first, usually a BOP or general liability, is the one least likely to answer the claims clients actually bring, and that mismatch is where the real money gets lost.
Here is what the gap costs
In one documented claim, a single set of targeting errors on a media buy produced a $540,000 demand from the client. Meanwhile, one unlicensed image can carry statutory damages of up to $150,000 if a court finds the infringement willful.
So this is the full program I would expect an established agency to carry:
Coverage |
What it pays for |
The agency claim that triggers it |
|---|---|---|
|
Professional liability (E&O) |
Defense and damages when a client says your work caused a financial loss |
Targeting error, missed launch, budget overspend, bad strategy |
|
Media liability |
Claims over what your content says or shows |
Copyright, trademark, defamation, privacy, misuse of likeness |
|
Cyber liability |
Breach response, third-party claims, ransomware, cyber crime |
A hacked client ad account, CMS, or CRM traced to your access |
|
General liability |
Third-party bodily injury and property damage |
A client trips at your office or a shoot damages a venue |
|
Property / BOP |
Offices, computers, production gear, business income |
Fire, theft, or damage that shuts down your studio |
|
Workers’ compensation |
Employee injuries and illness |
Required once you have employees, remote staff included |
|
EPLI |
Harassment, discrimination, wrongful termination claims |
A departing employee sues over how they were let go |
|
Extra limits above GL, auto, and employer’s liability |
A contract demands higher limits or a severe injury claim |
|
|
D&O |
Claims against leadership decisions |
Investors, a board, or a sale process |
|
Employee theft and some funds transfer fraud |
Money leaves the agency through theft or deception |
To keep it simple, I sort every agency claim through what I call The Three Doors: what you did (your service, answered by E&O), what you published (your content, answered by media liability), and what you touched (client systems and data, answered by cyber).
If any door has no policy behind it, you have a gap.
Book a call and we will run your agency through all three doors.
What professional liability coverage do marketing agencies actually need?
You need E&O written around every service you actually sell, with media liability included, continuous claims-made coverage, and limits that match your contracts. Yet the single biggest threat to that coverage is not the limit or the price. Instead, it is one short definition buried in the policy that most owners never read.
Here is the distinction I want every agency owner to remember: your policy covers the services it names, not the services you sell. A poorly drafted definition of professional services is the leading cause of coverage disputes in miscellaneous professional liability.
For example, if your policy defines your work as “market research services” and the claim involves paid social management, you may have no coverage at all.
Agencies add services every year, such as SEO, web development, influencer programs, and AI-assisted content.
However, their policy definitions rarely keep up.
So a strong errors and omissions policy for an agency should include:
Compare professional liability insurance options for creative agencies
Here is how the common options compare for a creative or marketing agency:
Option |
Campaign and service errors |
Content and IP claims |
Cyber |
Matches all your services |
Fits enterprise contracts |
|---|---|---|---|---|---|
|
General liability or BOP only |
No |
Very limited for agencies |
No |
No |
Rarely |
|
Online small-business E&O |
Yes, within its definition |
Sometimes, often limited |
Usually separate |
Often not |
Sometimes |
|
Combined E&O and media form |
Yes |
Yes |
Sometimes bundled |
Yes, if drafted well |
Usually |
|
Broker-built agency program (E&O, media, cyber coordinated) |
Yes |
Yes |
Yes |
Yes |
Yes |
Best professional liability insurance for marketing agencies and consultants
The best policy is not a brand name.
Instead, it is the one that pays when your specific work goes wrong.
From what I’ve seen, these are the tests that separate a policy that pays from one that looks good on a certificate:
Why doesn’t general liability cover the claims agencies really face?
General liability covers bodily injury and property damage, not the financial losses and content disputes that drive most agency claims. Surprisingly, even the “advertising injury” part of a general liability policy often fails agencies, because standard forms exclude insureds whose business is advertising. In other words, the one line that sounds like it was written for you usually isn’t.
The standard general liability form includes personal and advertising injury coverage. But that coverage is built for a business that advertises its own products, not a business whose product is advertising.
Standard forms carve out insureds in the business of advertising, broadcasting, or publishing for most of those offenses, and they also exclude most intellectual property claims.
So an agency that relies on general liability for a copyright or defamation claim is usually relying on coverage that was never there.
Here is how the same five situations play out across your policies:
Situation |
GL / BOP |
E&O |
Media liability |
Cyber |
|---|---|---|---|---|
|
A client slips in your office |
Yes |
No |
No |
No |
|
A targeting error wastes a client’s media budget |
No |
Yes |
No |
No |
|
An unlicensed stock image triggers a copyright demand |
Usually no for agencies |
Sometimes |
Yes |
No |
|
Ad copy is alleged to defame a competitor |
Usually no for agencies |
Sometimes |
Yes |
No |
|
A client’s ad account is hacked through your login |
No |
Limited |
No |
Yes |
As one agency owner put it, “E&O won’t cover any sort of cyber.”
That is often true, and it is exactly why the doors need separate policies.
Contact us and I will show you which door your current program leaves open.
What can a client actually sue your agency for?
Clients sue agencies for financial losses they blame on your work, for content that infringes or misleads, and for breaches that come through your access. Beyond clients, regulators and rights holders can come after the agency directly, even when the client approved everything, and that surprises almost every owner I talk to.
These are the claim patterns I see, and the documented cases behind them:
Real-world example (documented claim).
An established marketing agency with $61.9 million in revenue took over a client’s media planning and buying on a $10.6 million budget. Stretched thin, the team ran the campaign on the previous agency’s parameters instead of the client’s newer requirements. The client caught the targeting errors and demanded $540,000. The agency’s own analysis put the loss at $375,000. Because the agency had bought a media policy one month earlier, its carrier’s legal support mediated the dispute to $450,000. Without that policy, the full demand and every legal bill would have come out of the agency’s pocket.
We got sued by a client for campaign underperformance, what covers this?
Your E&O policy is the one that responds, as long as the claim alleges a negligent act, error, or omission in services your policy names.
Importantly, E&O generally pays for defense even when the allegation is groundless, which matters because a client does not need a real mistake to file.
So if your proposal guaranteed a specific return on ad spend, the claim can land outside coverage.
That is why I tell agencies to keep performance language in proposals as goals, not guarantees, and to report any threatened claim to the carrier right away, because late notice is its own reason for denial.
Does our marketing agency need cyber liability insurance coverage?
Yes, if you hold logins to client ad accounts, websites, CRMs, or analytics, you need cyber coverage. Cyber exposure follows access, not ownership. Many owners assume they are safe because they never store payment data, but the attack that actually hurts agencies usually comes through a borrowed login, not a stolen card number.
You manage client credentials, you publish to client websites, you connect tools to client CRMs, and you move audience data between platforms.
So if an attacker gets into a client’s systems through an account tied to your agency, you are part of the claim. A dedicated cyber insurance policy covers breach response, notification, forensics, ransomware, third-party claims from clients, and cyber crime.
On top of that, agencies are a natural target for invoice and payment fraud, because you send and receive large payments tied to media spend.
That is why cyber is now a core line in insurance for marketing agencies, not an add-on.
Our client data got breached, will our insurance cover the liability?
It depends on which policy you have and how the breach happened.
Specifically, a cyber policy with third-party liability coverage is what answers a client’s claim that your agency caused or contributed to the breach.
It can also pay for forensics, notification, and legal defense.
The first things I check after a breach are:
Top rated cyber liability insurance for digital marketing firms
So look for:
The limit on fraud is where I see the most damage.
When a wire scam hit, that was a $200,000 gap nobody caught.
That is why our social engineering coverage reviews start with the sub-limits, not the headline limit.
Book a call and we will check yours.
What limits and endorsements do enterprise clients require?
Enterprise contracts commonly require $1 million per occurrence and $2 million aggregate in general liability, $1 million to $2 million in E&O, cyber coverage, and specific endorsements. Still, meeting the contract minimum is not the same as being protected. A limit shared across all your clients, and reduced by legal fees, can disappear faster than owners expect.
So read the insurance section of every MSA for:
Two more traps catch growing agencies.
Also, an umbrella usually sits over general liability, auto, and employer’s liability, not over E&O, so higher E&O limits typically come from excess professional liability.
Contracts shape the fight, but only insurance funds it.
Contact us before you sign your next MSA.
How much does insurance for marketing agencies cost?
The cost is set by your exposure, not your headcount: services, the media spend you manage, client industries, contract limits, and your claims and security record. Two agencies with similar revenue can pay very different premiums. The reason usually comes down to what underwriters see in how you work, not what you earn.
Those numbers describe small shops buying standard packages.
By contrast, they tell you almost nothing about an agency running seven or eight figures of client spend.
These are the drivers that actually move your price:
Driver |
Why underwriters care |
|---|---|
|
Services mix |
Media buying, web development, and influencer work carry more severity than strategy alone |
|
Media spend under management |
Larger budgets mean larger losses when something goes wrong |
|
Client industries |
Healthcare, financial services, public companies, and government raise the stakes |
|
Limits and retentions |
Contract-driven $2 million limits cost more than $1 million |
|
Contractors and AI use |
More outside hands and tools mean more content and IP exposure |
|
Security controls |
Multi-factor authentication, backups, and access management affect cyber pricing |
|
Claims history |
Frequency and severity both matter at renewal |
Over the years I’ve watched a business owner save $2,000 a year on premiums and then face a $200,000 claim denial.
Book a call and we will build the number from how you actually operate.
How should your insurance change as your agency grows?
Your coverage should change every time your clients, services, team, or ownership change, not just at renewal. Most agencies wait for a contract or a claim to force the update. By then, the gap has usually existed for a year or more, and nobody noticed it until it cost money.
In my experience, insurance for marketing agencies goes stale at these growth triggers:
Best employment practices liability insurance for marketing teams
The best EPLI for an agency covers the way agency teams actually work: fast hiring, frequent turnover, remote managers, and staff who spend time at client offices.
Once you pass about 25 employees, in my view, this coverage is no longer optional.
When you compare EPLI options, check for:
What mistakes leave marketing agencies underinsured?
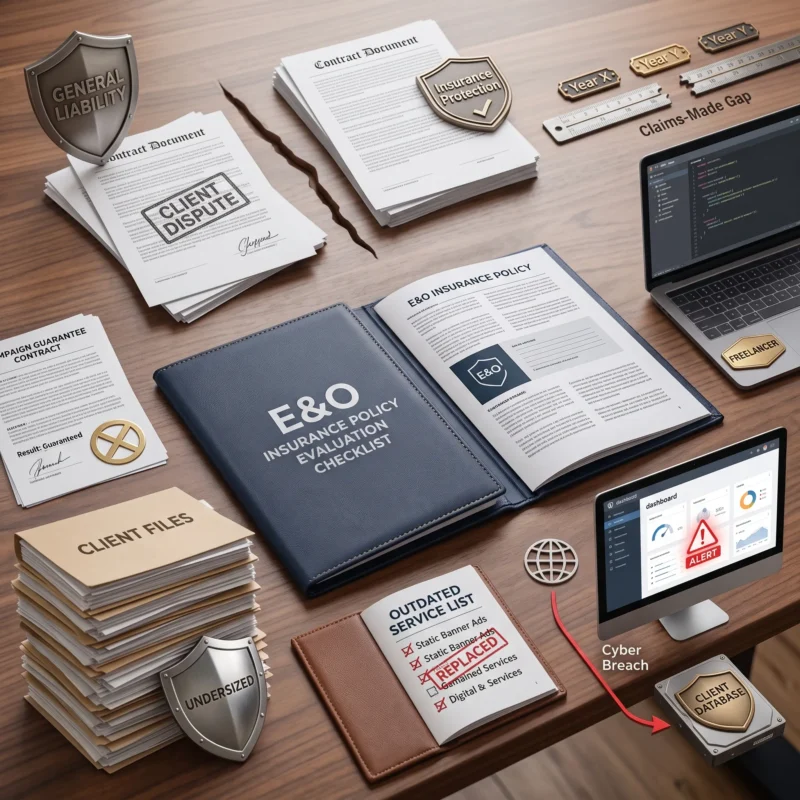
Most agencies are underinsured because of assumptions, not missing money. They believe general liability covers client disputes, that contracts transfer the risk, or that the policy they bought three years ago still fits. The most dangerous assumption, though, is the one nobody discovers until the claim is filed.
These are the mistakes I see most often:
If any of these sound familiar, start with our guide on whether your business is underinsured.
Then contact us for a line-by-line review.
Which insurance brokers specialize in marketing agency coverage gaps?
The brokers worth hiring read your contracts, your statements of work, and your policy wording together, then build E&O, media, and cyber as one coordinated program. Many agents can quote a policy. Far fewer can explain which of your claims would fall between two policies, and that is the skill that matters most.
Here is what I would look for in any broker handling your agency:
How does The Coyle Group handle insurance for marketing agencies?
We start with how your agency makes money and creates risk, not with a quote form.
Then we follow the same process for every agency client:
Our work with insurance for marketing agencies is built for established firms with real client contracts, payroll, and budgets under management.
If you are just starting out, a standard package may serve you for now. But if a single claim could hurt what you have built, book a call and let’s have a conversation.
Questions about Insurance For Marketing Agencies?
Get the Right Coverage for Your Marketing Agency
Most agency insurance is sold off a quick online form. But your agency doesn’t work like a standard business. You run client budgets, publish under their brands, and hold the keys to their accounts. Generic policies were never written for that.
I start with how your agency actually works, then read your contracts and policy wording line by line. When we review a program, we find at least one fatal mistake nine times out of ten.
We’re built for established agencies where one claim could undo years of work, and we stay in your corner when a claim hits.

This article was written by the CEO of The Coyle Group, Gordon B. Coyle, CPCU, ARM, AMIM, PWCA, who has over 40 years of experience working with business owners of all sizes and industries across the US, solving their insurance challenges.
Here’s how to take the next step
Schedule Your Insurance Confidence Assessment
In our 30-minute call, you’ll discover:
Not ready for a call?
Get Free Access to Our Gated Video:
“How to Finally Feel Confident in Your Coverage. “
And discover the exact system we use to help business owners eliminate hidden coverage gaps, stop overpaying, and finally feel confident in their protection.
What Peace of Mind Looks Like
Trusted by business owners across the U.S.
The Coyle Group is 1st class! Gordon and his team are knowledgeable, responsive, and attentive to detail. Gordon is that rare breed of professional who genuinely cares for his clients and works hard to exceed their expectations. I highly recommend them.


The insurance brokerage service was truly tailored to my needs, nothing like those big brokers who steer you toward random policies that don’t fit your profile. Thank you to the team for your help.

I was working with another broker and having difficulty acquiring General Liability coverage. A colleague recommended The Coyle Group. They were able to get coverage bound in just a couple of business days and a policy issued in ten days, and with a solid carrier at a competitive premium. Truly impressive results, plus it was a pleasure working with them. I highly recommend the Coyle Group!

If any business is looking to work with an insurance brokerage firm that is not only excellent at what the firm does, but one that deeply values the needs of the clients, then The Coyle Group is the firm for you. Give them a call and see for yourself. I can assure that you will quickly agree.

Want to know more?
See related blogs

The Crowdstrike Debacle and Cyber Insurance
Third Party Employment Practices Liability Insurance. Protect Your Business

Are You Overpaying or Underinsured on Your Business Insurance?
