
Quick Answer
Workers comp for remote employees works like coverage for on-site staff, but the state on the policy has to match where each person actually works. List every remote employee’s home state in Item 3A, buy state-fund coverage in Ohio, North Dakota, Washington or Wyoming, and use the right class code. Miss a state and that employee’s injury claim may not be covered.
Ready to check your coverage?
“We are being fined by NY state for not having comp coverage for last year.” That’s how one safety director described learning that whoever set up their policy “thought we only needed it for states where we have an office.” Another employer asked, “How do we account for remote workers in other states with no physical presence?” If your people work from home in states your policy doesn’t name, you may not have the coverage you think you have.
The Coyle Group is a commercial insurance agency that handles the complex, high-value risks other agencies don’t know how to structure, where the details in the policy are the difference between a paid claim and a denied one.
If you’ve hired someone in a new state, or moved inventory into a warehouse your insurer has never heard of, you’re not alone, and it’s fixable. We manage the market for you: we check every state your people work in and every location your property sits at, then make sure the right insurers see an accurate picture. I hold the PWCA designation in workers’ comp advising, and I audit programs for a living. The next step is a short, confidential call.
What does a missing state or location cost you?
A missing state can cost you a state fine, an uncovered injury claim and an audit bill, all for one employee. On the property side, an unreported warehouse may carry only a small, short-lived amount of automatic coverage. And nobody notices either gap until a claim, a state letter or an auditor finds it first.
The bills that show up
State penalties.
One small company that hired in seven states wrote, “Today we got hit with a $1,500 fine for failure to file a form we didn’t even know we needed to file.”
An injury nobody insured.
The claim can be excluded, and the medical bills and lost wages become your problem.
Audit surprises.
Payroll found in an unlisted state gets charged back.
Property that’s barely covered.
At most $250,000 of automatic building coverage and $100,000 for contents, for 30 days.
Why this keeps growing
The Bureau of Labor Statistics reports that in 2025, 22.4% of people at work teleworked or worked at home for pay, about 35.4 million people, and 10.5% did so for all of their hours.
What is workers comp for remote employees?
Workers comp for remote employees is the same workers compensation policy that covers your office staff, applied to people who work from home or from another state. It pays medical bills and lost wages when an injury is work-related. However, every state where someone works has to be set up correctly on the policy.
Workers comp for remote employees in simple terms
Workers compensation pays an injured employee’s medical care and part of their lost wages, and in exchange the employer is generally protected from most injury lawsuits; see how workers comp insurance works. For a remote worker, the question is whether the injury came from the job, and whether the job’s state is on your policy.
Where this fits in my common mistakes series
In my last video, I introduced this multi-part video series focused on the common errors, mistakes, and failures I have documented in the coverage programs we have reviewed in the past for prospective clients. Last time we discussed missing named insureds, and today we’re going to talk about missing locations.
Watch: common mistakes part 2
Having all your locations properly identified predominately falls into two policy buckets: property insurance and workers compensation. Remote work has made workers comp the bigger exposure, so it gets most of this article, but the property side follows.
Key aspects at a glance
Here’s how a standard workers compensation policy handles remote and out-of-state employees:
Policy feature |
What it does |
Remote-work takeaway |
|---|---|---|
|
Item 3A (Information Page) |
Lists states with known employees or locations |
Put every remote employee’s home state here |
|
Item 3C (Other States) |
Backup for unexpected, temporary work |
Not a substitute for a permanent remote hire |
|
Part Two |
Employers liability for injury lawsuits |
Not included in monopolistic state funds |
|
Class code |
Sets the rate for each type of work |
Home-based clerical staff may qualify for Code 8871 |
Which state’s workers comp law applies to a remote employee?
Usually the state where the employee lives and does the work, though the state where they were hired can also have a claim. There’s no single national rule, so one injury can touch two states’ laws. That’s why the policy must name the state before anyone gets hurt.
The workers comp policy and its benefits are state specific, so it’s required to have the states where an insured has locations OR employees identified in section 3A of the policy (Item 3A on the Information Page). It doesn’t matter if the employee is full time or part-time: failure to have that employee’s state on the policy can exclude coverage for that employee if they’re injured during a work-related accident and a claim is reported.
The second bucket of insurance this happens with increasing regularity is with workers compensation. It’s happening more often today because of virtual workers who work in different states than that of the named insureds. A new remote hire, or an employee who moves, creates a new state on day one.
Item 3A vs Item 3C: which one covers your remote hire?
A permanent remote employee is known exposure, so that state belongs in 3A. Under standard NCCI wording, 3C coverage generally applies only if the employee was hired or principally employed in a 3A state, and it can require notice within 30 days.
|
|
Item 3A |
Item 3C |
|---|---|---|
|
Purpose |
Known, ongoing employees or locations |
Work that might start unexpectedly |
|
Premium |
Charged up front on each state’s payroll |
None until work begins there |
|
Right for |
Permanent remote employees, branches |
Short trips, a surprise job site |
Some states don’t recognize your home-state policy
The Virginia Workers’ Compensation Commission says Virginia requires Virginia coverage for work performed in Virginia and has no reciprocity with any other state. It also says Virginia must be listed in Item 3A, because 3A is for known exposure. We check every state by name.
Monopolistic states need their own coverage
The Hartford lists four states where private insurers can’t write workers comp: Ohio, North Dakota, Washington and Wyoming. You buy coverage from the state fund. Those funds don’t include employers liability, so you also need stop gap coverage, explained in our guide to employers liability in workers comp.
Hiring in a state you’ve never had employees in? Book a call and we’ll tell you what that state needs before the start date.
Are injuries at home covered by workers comp?
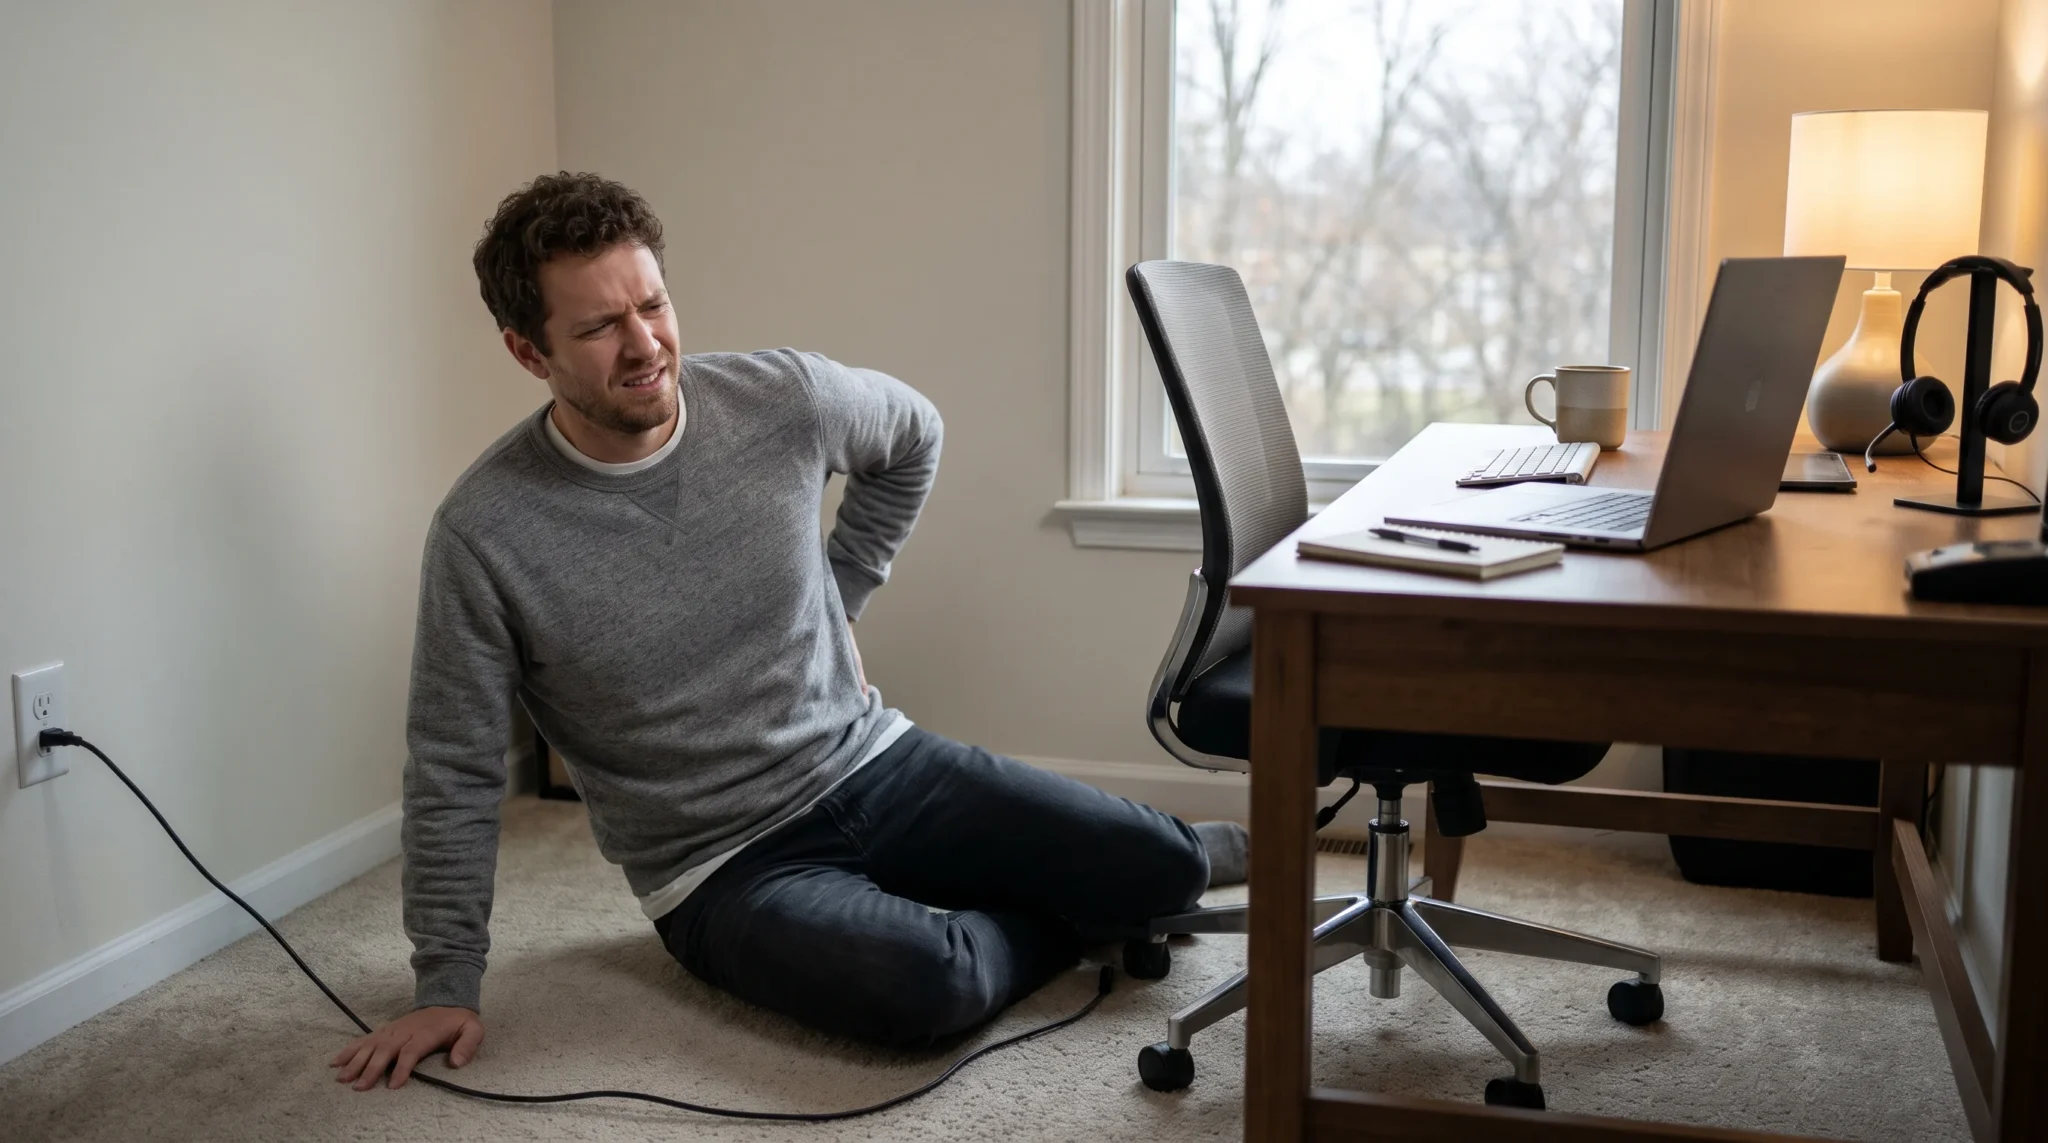
Yes, when the injury arises out of and happens in the course of the job, even at the kitchen table. A home office doesn’t make every household accident a work injury, and it doesn’t create an exclusion either. Courts look at what the employee was doing, when, and whether the hazard came from the work.
The two-part test
Arising out of employment.
Was there a causal link between a work risk and the injury.
In the course of employment.
Did it happen during work time, while doing the job or something incidental to it.
Breaks can still count
The Hartford describes the personal comfort doctrine: brief, necessary breaks like refilling a water bottle or stretching can stay within the course of employment. Courts still split on similar facts. A Florida appeals court denied a remote adjuster who tripped over her dog getting coffee, while a Pennsylvania court allowed a claim for a remote employee who fell on her stairs after getting juice during work hours.
Examples of covered and non-covered home injuries
Here’s how the line usually falls, though each state decides its own cases:
Likely covered |
Likely not covered |
|---|---|
|
Repetitive strain from work typing |
Hurting yourself doing household chores |
|
Tripping over a work laptop cord during work hours |
Injuries while walking the dog off the clock |
|
A fall on the way back from a short break during work hours |
Injuries from a purely personal hazard |
What to document when a remote employee reports an injury
The arrangement.
A written remote-work policy with the approved location and hours.
The activity.
What the employee was doing, and whether it was work or a short break.
The timing.
When it happened and when it was reported.
The setting.
Photos of the workspace and any equipment involved.
See our guide on handling a workers comp claim.
Who needs to pay attention to remote workers comp?
Any employer with even one person working outside the state listed on the policy, which today means most growing companies. The risk is highest where hiring moves fast and payroll is handled by someone outside the insurance conversation, like a payroll provider, a PEO or an HR team that never talks to the broker.
Industries where we see this most
Professional services and financial firms.
Staff who relocated after 2020.
Technology companies.
Engineers hired wherever the talent is.
Wholesalers and distributors.
Field sales reps working from home across a territory.
Multi-location businesses.
New branches and overflow warehouses.
Remote contractors are a separate question
A 1099 remote worker may not be your employee, but a state can decide otherwise, and their payroll can then show up on your audit. Our article on employee or independent contractor explains the tests.
Watch: What Does Workers Compensation Cover?
What does workers comp for remote employees cost?
Remote clerical employees are usually among the least expensive people to insure, because the rate reflects low-hazard office work. What changes the price is where they live, since each state files its own rates, and whether their payroll is reported in the right state and class code at audit.
Watch: How are Workers Compensation Premiums Calculated?
What moves the price (as of November 2026)
There’s no national rate for remote employees, so here’s what drives your number:
Cost factor |
How it moves your premium |
What to check |
|---|---|---|
|
Employee’s state |
Each state files its own rates |
Payroll split by state on the policy |
|
Class code 8871 vs 8810 |
Both are clerical codes; 8871 is for qualifying telecommuters |
That home-based staff meet the 8871 rules |
|
Payroll |
Premium is charged per $100 of payroll |
Estimated payroll by state, updated mid-term |
|
Experience mod |
Claims history raises or lowers the rate |
Your experience mod worksheet |
|
Minimum premium |
A one-person state can carry a minimum charge |
Whether small states are priced sensibly |
|
Monopolistic state fund |
A separate policy and premium |
Ohio, North Dakota, Washington, Wyoming |
For figures by industry, see what workers compensation insurance costs.
Code 8871 for home-based clerical staff
In New York’s rating bureau definition, Code 8871 applies to telecommuter clerical employees working from a residence office separate from the employer’s location, who spend more than 50% of their time on clerical or drafting work from home. Anyone regularly exposed to your operations doesn’t qualify. See our guide to workers compensation class codes.
Watch: Workers Comp Class Codes, What Are They For? 2025
The audit is where missing states show up
At the end of the term, the insurer audits actual payroll, and payroll in a state that wasn’t on the policy is where surprise bills come from. One small nonprofit wrote that after its audit it was “required to pay them the amount owed for this employee.” See our workers comp audit guide and insurance premium audits.
What underwriters look at
Insurers weigh a handful of factors:
Factor |
Why underwriters care |
What to have ready |
|---|---|---|
|
Payroll by state |
Rates and rules are state specific |
Every employee’s work state and payroll |
|
Job duties at home |
Decides 8871, 8810 or a higher code |
Job descriptions for remote roles |
|
Remote-work policy |
Shows hours, location and safety rules exist |
Your written remote-work policy |
|
Loss history |
Predicts future claims |
Five years of loss runs |
|
Monopolistic exposure |
Needs a separate state-fund policy |
Names and states of those employees |
Not sure your payroll is split by the right states? Contact us and we’ll compare your policy to your payroll report.
What about locations that never made it onto the property policy?
An unreported location may have only temporary, capped coverage, or none. This is the first of the two buckets, and it mirrors the remote-employee problem: the business changed and the policy didn’t. I call it the new-location blind spot, and it usually starts small.
The first is property insurance. Where I have seen this happen most often is with temporary locations such as non-owned warehouses. Inventory can overflow at one location and it gets stored at a new location and the insured fails to notify their agent of this change. And if this temporary location becomes permanent, the problem of it not being reported can run for several years.
How automatic coverage for new locations works
While many property policies provide sub-limits for newly purchased or leased locations, there are limits on the amount of coverage and the duration of coverage. So if there’s a loss at this temporary location in the future, there can be limited coverage or no coverage. Here’s the standard commercial property form:
Newly acquired property |
Standard automatic coverage |
|---|---|
|
Building you acquire or build |
Lesser of 25% of your building limit or $250,000 per building |
|
Business personal property there |
$100,000 at each building |
|
How long it lasts |
Ends at the earliest of 30 days, policy expiration, or reporting the values |
Your own policy controls, and many of these extensions apply only with 80% coinsurance or more (see coinsurance explained). For more, read does business insurance cover a new location.
Watch: Commercial Property Insurance for Small Businesses
Other location problems we find
Other property location-based problems include locations with incorrect addresses or new locations purchased but never reported. Again, it’s not a problem until it’s a problem. Our guide to commercial property insurance for small businesses covers how schedules and limits should be set.
Real-world example: the state nobody added.
A company set up workers comp only for states where it had an office or an active project, so nobody listed its New York remote staff. The safety director found out when New York fined the company for having no comp coverage for the prior year.
What are the benefits of getting your states and locations right?
The claim gets paid, the state doesn’t fine you, and the audit matches your budget. None of that requires a bigger policy. It requires an accurate one, and fixing it usually costs far less than a single uninsured injury or a warehouse loss.
Claims get paid.
Your business isn’t funding medical bills directly.
No state penalties.
Coverage gaps that draw fines are avoidable.
Predictable audits.
No back-charges for unlisted states.
Property paid at full value.
Not a 30-day, capped extension.
There’s a difference between being covered and being adequately covered. One checks a box. The other protects your business. Our page on what workers comp covers lists the benefits your employees are entitled to.
How do you check your own policy?
Pull your workers comp Information Page and your property schedule, and compare them to your payroll report and your real addresses. If a state or location appears on one list and not the other, that’s a gap. Most owners can do the first pass in under an hour.
A five-step self-check
- List every work state. Use payroll by employee.
- Compare to Item 3A. Every state with a regular employee should be there.
- Check the four monopolistic states. They need state-fund policies plus stop gap.
- Check class codes. Remote clerical staff need clerical codes.
- Compare locations. Every warehouse belongs on the property schedule.
Then use the commercial insurance renewal checklist.
Make the review a habit
The solution is that locations are reviewed during a renewal review or mid-term review. Unfortunately, too many brokers don’t perform these with clients, so the locations go unreported until there’s a loss. A business insurance review or business coverage review at renewal, plus a mid-term check, catches most new hires and new sites.
How to lower remote injury risk
Write a remote-work policy.
Set hours, the approved work location and how to report an injury.
Use a home-office checklist.
Cords, lighting, chair and desk height, and a clear path.
Support ergonomics.
Equipment or a stipend reduces strain claims.
Want a second set of eyes on your Information Page? Book a call and we’ll go through it line by line.
What should you watch out for?
Watch for coverage you assume exists because someone else runs payroll, because a state sits in the wrong part of the policy, or because a location never reached the schedule. These problems don’t show up when you buy. They show up at audit or claim time.
Exclusions and gotchas
Personal activities at home.
Injuries from purely personal hazards aren’t compensable.
Payroll-bundled comp.
A policy bought through a payroll provider still needs the right states and codes.
Red flags your remote workers comp setup has gaps
Item 3A lists only your headquarters state.
Your payroll report shows employees elsewhere.
Nobody has asked about new hires, states or locations in the last year.
Your program is being processed, not managed.
Remote office staff carry your operations class code.
You’re likely overpaying.
You have an employee in a monopolistic state.
And no state-fund policy or stop gap.
Your last audit added payroll in a state you didn’t know about.
The gap was there all year.
A “temporary” warehouse isn’t on the property schedule.
It’s been there more than 30 days.
I explain why these slip through in two big problems with business insurance.
Watch: The Definitive Workers Compensation Audit Guide
Why work with The Coyle Group on workers comp for remote employees?
Because we check where your people and property actually are before any insurer sees your account, and we keep checking every year. I hold the PWCA designation, and Donna Richard, our Senior Account Manager, has 20 years in workers’ comp and manages multi-state programs.
So, to sum it up, insureds need to be aware of their locations and have them properly listed in their policies. The two most location dependent policies are property and workers comp, but it may also be critical for other policy forms as well.
The Coyle Process
Diagnose the risk.
We map every work state, location and class code against your policy.
Identify the right insurers.
Those that handle multi-state and remote exposure well.
Explain where we’re going and why.
You see the plan first.
Bring viable options back.
You compare them side by side.
The result is fewer applications, fewer duplicate requests and one point of contact, the discipline behind the diagnostic insurance review.
About shopping your coverage
Comparing is smart. Shopping indiscriminately is different: duplicate applications, the same insurers approached by several brokers, and a multi-state risk misclassified by someone who doesn’t handle remote exposure every day. You don’t need five brokers shopping your insurance. You need one capable broker making sure the right insurers compete for your business.
Who this isn’t right for
If you’re looking for someone to rubber-stamp what you already have at a lower price, there are brokers who will do that. We’re not one of them. If you want a one-time policy and no one checking in, we’re not the right fit either, because we re-underwrite every year. And if you’re very small, with one location and no remote staff, a basic packaged policy may serve you well, and I’ll tell you so.
Your next step: a 15-minute call, not an application
If you already have coverage.
We’ll do a confidential review of your Information Page, forms, exclusions and conditions against your payroll by state.
If you need new coverage.
We’ll build the underwriting picture with you and identify which insurers fit your states and operations.
As always, if you’ve got concerns about potential shortfalls, gaps and overlaps in your insurance program, or want to learn more about our process, I’d love to hear from you. No pressure, no obligation. You have questions, and we have the answers.
Ready to find out whether every employee is really covered? Book a call and let’s have a 15-minute conversation.
Frequently Asked Questions
Author’s Expertise
This article was written by the CEO of The Coyle Group, Gordon B. Coyle, CPCU, ARM, AMIM, PWCA, who has over 40 years of experience working with business owners of all sizes and industries across the US, solving their insurance challenges.


