
Contract Research Organization Insurance
What Sponsor Contracts Require and Where CROs Get Exposed
Index

Gordon B. Coyle
CEO, The Coyle Group
845-474-2924
How to get started
Quick answer.
A CRO’s insurance program is built around professional liability (E&O) as the primary line, layered with clinical trial liability, cyber, general liability and property, workers’ compensation, D&O, and umbrella, sized to what your sponsor contracts require rather than your company’s revenue. It is common to see sponsors contractually require clinical trial or product liability limits of $10 million per claim and $10 million aggregated annually, so the real question is never whether you “have insurance.” It’s whether your program matches what the contract in front of you demands.
Now you have to prove your program matches it before you can sign.
Most contract research organizations I talk to are mindful of costs and assume this kind of coverage should not break the bank.
Then they read the clause again and realize they are not sure their current policy satisfies a single line of it.
That gap between what a sponsor demands and what a CRO actually carries is where deals stall and claims get denied.
The Coyle Group is a commercial insurance agency that handles the complex, high-value risks other agencies don’t know how to structure, where the details in the policy are the difference between a paid claim and a denied one.
Over 40 years I have watched businesses hand off a certificate that looks compliant on paper and then discover, at the worst possible moment, that it does not respond.
Contract research organization insurance is not one policy you buy and forget.
It is a coordinated stack, sized to your sponsor contracts, that has to hold up when a study goes sideways.
The problem in your words, and how we approach it
You received a sponsor MSA or CTA (Clinical Trial Agreement) with an insurance schedule you are not sure you meet, and you need to know what to fix before you sign.
We read the contract first, map it against your current coverage line by line, and close the gaps so your certificate is not just compliant but claim-ready. Nine out of ten programs we review have at least one fatal flaw.
Book a call and we will pressure-test yours against your biggest sponsor contract.
What is contract research organization insurance, and why isn’t a standard business policy enough?
Contract research organization insurance is a coordinated set of coverages built around professional liability (E&O), clinical trial liability, and cyber, sized to what your sponsor contracts require rather than to your revenue. Here is the part that catches people: a standard business policy actively works against you. It looks like protection, but it leaves out the exact lines a sponsor checks for.
A CRO sells a service, running, monitoring, and managing studies, so your primary exposure is professional, not product.
In my experience, the recurring mistake is buying a generic small-business package or business owners policy that carries general liability but excludes or under-sizes the two lines that actually matter here: professional liability and clinical trial liability.
It is common to see sponsors contractually require minimum clinical trial or product liability limits of $10 million per claim and $10 million aggregated annually.
That is a six-figure or seven-figure exposure sitting behind a policy that felt affordable.
This page is part of our broader life sciences insurance practice, and CRO coverage is one of the most misunderstood corners of it.
That distinction is exactly why a CRO’s core exposure is professional, not product.
Who needs this coverage:
Not every CRO needs the full stack on day one.
An early-stage CRO doing only regulatory consulting or data management, with no direct contact with trial subjects, usually does not need its own clinical trial liability tower yet.
Professional liability sized to that narrower scope, plus a strong additional-insured position on the sponsor’s policy, can be enough until the work expands into monitoring, site management, or direct subject contact.
Who is actually liable when a trial subject is injured, the sponsor or the CRO?
The sponsor bears the risk of bodily injury from the drug itself; the CRO is responsible for following the trial protocol. Absent proven negligence, a CRO does not carry liability for an adverse drug reaction. Sounds clean, until you learn how these lawsuits actually get filed, because the split on paper is not the split in a courtroom.
When a serious bodily-injury claim happens, it is common for multiple parties to be named, and the CRO is almost always one of them.
If the sponsor lacks the financial resources or insurance to stand behind its share, the CRO can be left paying a far greater portion than it should.
From what I have seen, this contingent bodily-injury exposure is the single most underestimated risk a CRO carries.
Exposure |
Sponsor’s responsibility |
CRO’s responsibility |
|---|---|---|
|
Bodily injury from the study drug or device |
Primary, via clinical trial or product liability policy |
Contingent, if named in a suit or if negligence is alleged |
|
Protocol execution, monitoring, data management |
Sets the protocol, holds the IND (Investigational New Drug application) |
Primary, via professional liability (E&O) |
|
Regulatory submission errors |
Shared, sponsor owns the filing |
Primary, if the CRO prepared it |
|
Data breach of PHI or trial data |
Shared |
Primary, as a HIPAA Business Associate |
|
Being named in a subject-injury lawsuit |
Yes |
Yes, nearly always |
Contact us if a sponsor is trying to shift subject-injury liability onto your contract; that clause deserves a close read before you sign.
What insurance does a CRO actually need?
A CRO typically needs seven core lines, driven by sponsor contracts more than company size: professional liability (E&O) as the primary line, clinical trial liability for subject injury, general liability and property as the floor, cyber for trial data and PHI, workers’ compensation, D&O once outside capital arrives, and umbrella or excess when a contract demands a combined limit. The order you buy them in matters as much as the list, but start with what each one does.
Here is the stack, and why each line earns its place:
Even a properly built program has limits.
None of these are reasons to skip coverage.
They are reasons to read the exclusions page before you sign, not after a claim.
Book a call and we will map this stack to the specific contracts on your desk.
E&O vs clinical trial liability, what’s the difference?
E&O covers financial loss from how you performed the service; clinical trial liability covers bodily injury to a human subject. They are not interchangeable, and assuming one covers the other is where CROs get burned. Most people assume they are basically the same thing with different labels, and that assumption is exactly what a sharp sponsor is testing when it lists both separately.
Think of it this way.
If a monitoring lapse causes a data-integrity problem that delays drug approval and costs the sponsor money, that is an E&O claim: financial harm from your professional work.
If a participant is injured during the study, that is bodily injury, and neither your E&O nor a general liability policy is built to pay it; that is clinical trial liability territory.
A carrier put it plainly: CROs face vicarious product liability, malpractice from failing to follow protocol, and errors and omissions from improper filing that delays approval.
Three different triggers, three different responses.
One policy cannot quietly stand in for the others.
Feature |
Professional liability (E&O) |
Clinical trial liability |
|---|---|---|
|
What it covers |
Financial loss from your professional services |
Bodily injury to trial subjects |
|
Typical trigger |
Protocol deviation, monitoring failure, data or filing error |
Adverse event or injury during the study |
|
Who usually requires it |
Nearly every sponsor MSA |
Protocol, ethics committee, sponsor CTA |
|
Common form |
Claims-made (needs continuous coverage and tail) |
Placed per study or as an ongoing tower |
|
Does a BOP cover it? |
No |
No |
Why a generic business owners policy leaves a CRO exposed
A business owners policy is only the floor. It bundles general liability and property, but it leaves out the three lines that define research risk: professional liability, clinical trial liability, and cyber. A sponsor reviewing your certificate at contract time will catch the gap, and sometimes a claim finds it first, which is the more expensive way to learn the lesson.
The danger is not that a BOP is bad.
It is that it looks like enough.
From what I have seen, a CRO will hand over a certificate believing it is covered, and the “professional services” definition in the policy either excludes clinical trial work or is written so narrowly that a protocol-deviation claim falls outside it.
That quote is not marketing.
It is what we find, over and over, when we audit programs.
The fix is rarely expensive. The exposure of not fixing it can be enormous.
Real claim scenario: the randomization error.
One of the most frequently encountered claims in the CRO space is a randomization error or a wrong-patient medication incident. Picture a subject who receives the wrong study arm because of a data-handling mistake by the CRO. The injury is bodily, but it is entangled with the sponsor’s drug. The CRO gets named. If the E&O form excludes clinical trial work, and there is no clinical trial liability tower, and the sponsor’s policy does not list the CRO as additional insured, the CRO can be left funding defense and settlement on a claim its “compliant” certificate never actually covered. This is the difference between certificate-compliant and claim-ready.
Contact us for a second opinion on whether your current program is claim-ready or just certificate-compliant.
What do sponsor MSAs and CTAs require, and what’s negotiable?
Sponsor agreements typically require specific limits, additional-insured status, primary and non-contributory wording, a waiver of subrogation, and carriers rated A or better by A.M. Best. Some of those terms are movable and some are not, and knowing which is which is how you keep a contract from stalling. The trick is to bring your program into alignment before the certificate goes out, not after the sponsor bounces it back.
What sponsors most commonly demand, in plain terms:
What is usually negotiable, and what is not: for major pharma sponsors, the hard limits are typically immovable.
Additional-insured wording often allows an alternative endorsement.
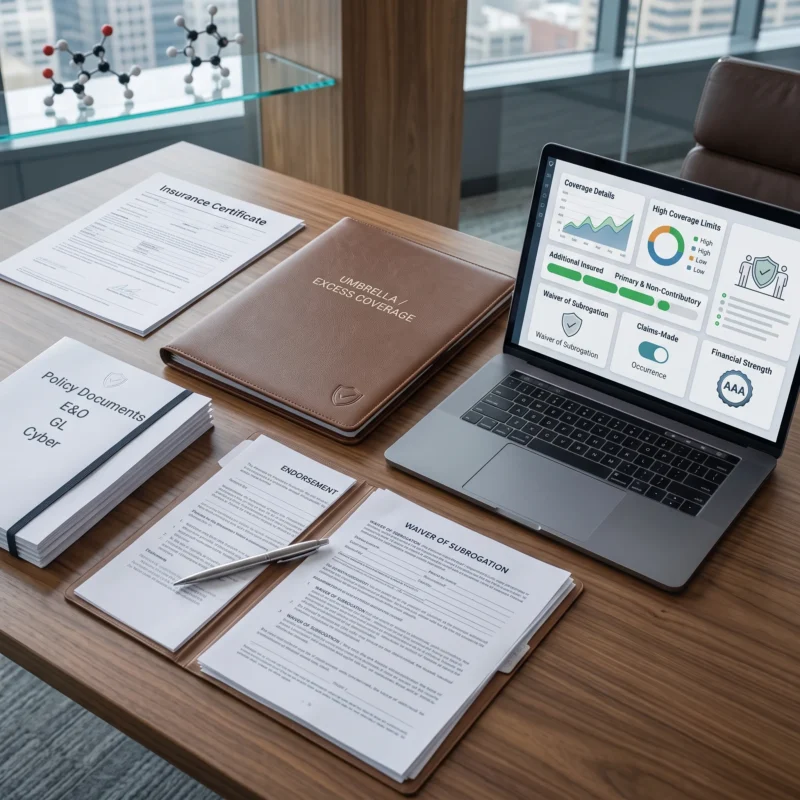
Notice-of-cancellation language can sometimes move to standard wording, and aggregate-per-project endorsements are frequently achievable.
A CRO operates under FDA Good Clinical Practice obligations, which is why sponsors treat these clauses as non-optional rather than boilerplate.
Knowing where you have leverage, and where you do not, keeps you from over-buying or from promising something your policy cannot deliver.
Book a call before you counter-sign an insurance exhibit; we will tell you what to accept, what to push back on, and what to bind.
Do CROs need cyber insurance if they handle PHI and clinical data?
Yes, and for a CRO it is a core line, not an optional one. You hold trial datasets, subject PHI, and sponsor-proprietary information, which makes a breach a matter of when, not if, and makes you a HIPAA Business Associate with direct legal obligations. Sponsors increasingly write a specific cyber limit and data-handling terms right into the CTA, so this is quickly becoming a compliance item, not just a risk-management one.
Cyber covers breach response, notification, forensics, and liability when trial data or PHI is exposed.
The exposure is real and large: in 2024, the HIPAA Journal recorded 725 data breaches reported to the HHS Office for Civil Rights, affecting more than 275 million records.
Because you handle participant PHI, you carry direct duties under federal rules for HIPAA Business Associates, including breach notification and safeguards.
Our cyber insurance practice sizes these programs for data-heavy businesses like yours.
How much does contract research organization insurance cost?
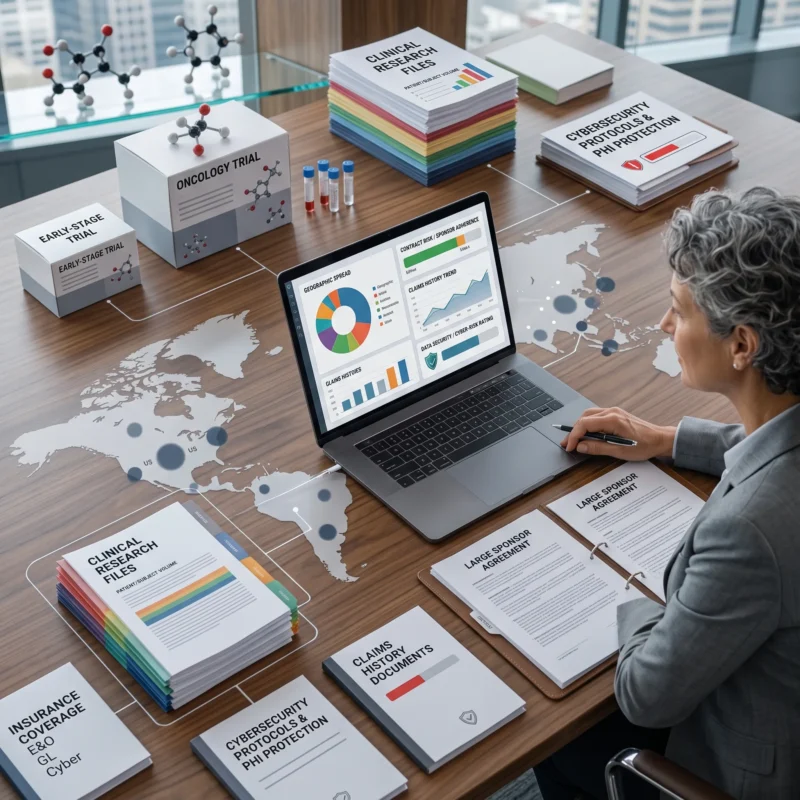
There is no honest flat price, and anyone quoting you one is guessing. The cost of contract research organization insurance is driven by your sponsor contracts, trial phase, indication, subject count, geography, and claims history, not by your company’s revenue. That is a feature, not a frustration, because it means limits scale to the deals you actually sign rather than to an arbitrary size band.
Be careful with generic small-business pricing you see online.
Clinical research, human-subject exposure, PHI, sponsor indemnities, and specialized E&O underwriting make CRO coverage materially different from ordinary agency or consulting insurance.
What actually moves your premium:
Contact us for a real range built around your contracts, not a website estimate.
How should a CRO build its insurance program, in the right order?
Build it in sequence, not all at once: professional liability, general liability, and workers’ comp first as the floor; clinical trial liability before you enroll a single subject; cyber from day one; D&O when outside capital arrives; and umbrella when a sponsor contract requires a limit your primary policies cannot reach. Getting the order right is what keeps you compliant at each stage without over-buying early. I call this the contract-first build, and it exists because sponsors, not calendars, dictate when each line becomes urgent.
The sequence we use with CROs:
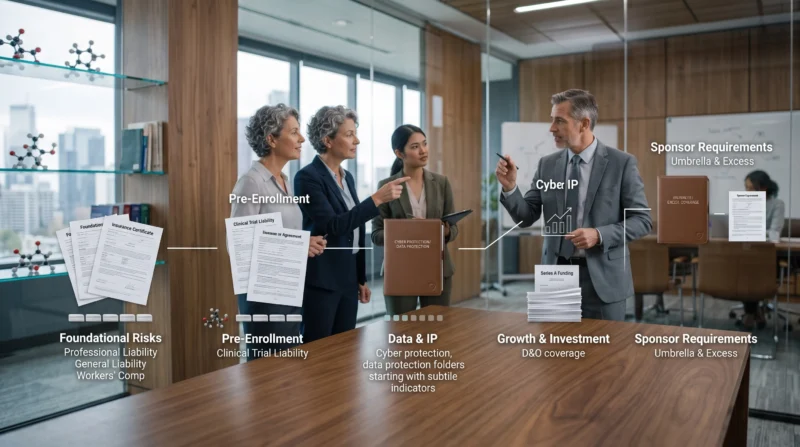
Running every MSA or CTA against your current program before signing catches these before they become a compliance problem or a denied claim.
This is the same discipline we bring to a full life sciences insurance program, and it is why we tell clients to treat insurance as an ongoing relationship, not a one-time purchase.
How The Coyle Group structures contract research organization insurance
We read the contract before we read the quote. Our approach to contract research organization insurance starts with your sponsor MSAs and CTAs, maps them line by line against your current coverage, and closes the gaps so your certificate is claim-ready, not just certificate-compliant. That order is deliberate, because a program built to satisfy a checklist and a program built to survive a claim are rarely the same thing.
Insurance is not a commodity, and CRO coverage proves it.
The cheapest package is cheap for a reason: narrow definitions, low limits, and exclusions you do not find until a claim exposes them.
Over 40 years I have seen the same pattern repeat, a business saves a little on premium and then faces a claim its policy was never built to pay. My job is to make sure that story does not end with your name on an uncovered lawsuit.
A good broker reads the gaps in what you already carry, understands the nuances of clinical research, and negotiates the endorsements sponsors demand.
If your current broker is processing renewals without ever reading your sponsor contracts, it is worth asking what your insurance broker should be doing for a business as regulated as yours.
For CROs that also handle product or manufacturing exposures, we coordinate this with related lines like private label supplement insurance so nothing falls between policies.
Book a call and bring your toughest sponsor contract. We will tell you exactly where you stand.
Quick answers and buying considerations
Ready to make sure your coverage matches your contracts? Book a call or contact The Coyle Group and bring your toughest sponsor MSA.
We will map it against your program and show you exactly where you are covered and where you are exposed.
Questions about Contract Research Organization Insurance?
Get the Right Coverage for Your CRO Insurance
We read your sponsor’s MSA or CTA before we ever quote a policy, so your program is built to satisfy the contract and survive a claim.
Nine out of ten programs we review have at least one fatal flaw. We find it before your sponsor does.
That is the difference between certificate-compliant and claim-ready, and it is the only kind of coverage we build.

This article was written by the CEO of The Coyle Group, Gordon B. Coyle, CPCU, ARM, AMIM, PWCA, who has over 40 years of experience working with business owners of all sizes and industries across the US, solving their insurance challenges.
Here’s how to take the next step
Schedule Your Insurance Confidence Assessment
In our 30-minute call, you’ll discover:
Not ready for a call?
Get Free Access to Our Gated Video:
“How to Finally Feel Confident in Your Coverage. “
And discover the exact system we use to help business owners eliminate hidden coverage gaps, stop overpaying, and finally feel confident in their protection.
What Peace of Mind Looks Like
Trusted by business owners across the U.S.
The Coyle Group is 1st class! Gordon and his team are knowledgeable, responsive, and attentive to detail. Gordon is that rare breed of professional who genuinely cares for his clients and works hard to exceed their expectations. I highly recommend them.

The insurance brokerage service was truly tailored to my needs, nothing like those big brokers who steer you toward random policies that don’t fit your profile. Thank you to the team for your help.

I was working with another broker and having difficulty acquiring General Liability coverage. A colleague recommended The Coyle Group. They were able to get coverage bound in just a couple of business days and a policy issued in ten days, and with a solid carrier at a competitive premium. Truly impressive results, plus it was a pleasure working with them. I highly recommend the Coyle Group!

If any business is looking to work with an insurance brokerage firm that is not only excellent at what the firm does, but one that deeply values the needs of the clients, then The Coyle Group is the firm for you. Give them a call and see for yourself. I can assure that you will quickly agree.

Want to know more?
See related blogs

The Crowdstrike Debacle and Cyber Insurance
Third Party Employment Practices Liability Insurance. Protect Your Business

Are You Overpaying or Underinsured on Your Business Insurance?
