
Product Recall Insurance for E-Commerce
The Coverage Amazon Never Told You to Buy
Index

Gordon B. Coyle
CEO, The Coyle Group
845-474-2924
How to get started
TL;DR. Executive Summary
Product recall insurance for e-commerce pays your own first-party cost to pull a defective or contaminated product off Amazon, Walmart, and your DTC store, plus the income you lose while the SKU is down.
Online sellers of supplements, cosmetics, food, toys, electronics, and private-label goods carry the most exposure, and a single recall commonly runs into seven figures.
Your account balance swings negative because the marketplace clawed back gross sales, kept its commission, and hit you with a forced 14-day removal notice.
Now you are staring at hundreds of units you can never sell, a dead listing, and a support queue that feels like talking to a brick wall. That is the moment most sellers learn their insurance was never built for this.
Here is the uncomfortable part. You almost certainly already bought insurance, because the marketplace made you. What you bought does not touch a single dollar of what you are now facing.
The Coyle Group is a commercial insurance agency that handles the complex, high-value risks other agencies don’t know how to structure, where the details in the policy are the difference between a paid claim and a denied one. Recall exposure is exactly that kind of detail.
Below, you will see exactly what recall coverage pays for, how it differs from liability, what triggers it, how underwriters decide whether to quote you, and how to size your limits.
What happens to an online seller when a product gets recalled?
A recall for an online seller means pulling the product from every channel at once, refunding buyers, destroying stranded inventory, and losing the income from a dead listing, all on your own dime. The first shock is rarely the safety issue itself. It is discovering how fast the marketplace machinery turns against your cash flow while your coverage sits silent.
When a defect, contamination finding, or safety complaint surfaces, the sequence tends to move fast:
The numbers behind this are not small.
Even a contained event across a few thousand units can run well into six figures once you total notification, reverse logistics, destruction, refunds, and lost margin. For a business running on inventory-financed cash flow, that is not a bad quarter. That is an extinction event.
Want a plain answer on your specific exposure? Contact us, and we will walk through your product line with you.
What is product recall insurance, and what does it actually cover for e-commerce?
Product recall insurance is a standalone policy that pays your first-party cost to remove an unsafe or defective product from the market and get your business back on its feet. For an online seller, that means the physical and financial mechanics of the pull itself, not lawsuits. What surprises most sellers is how far the coverage reaches beyond simple shipping.
A well-structured product recall insurance policy for an e-commerce brand typically funds:
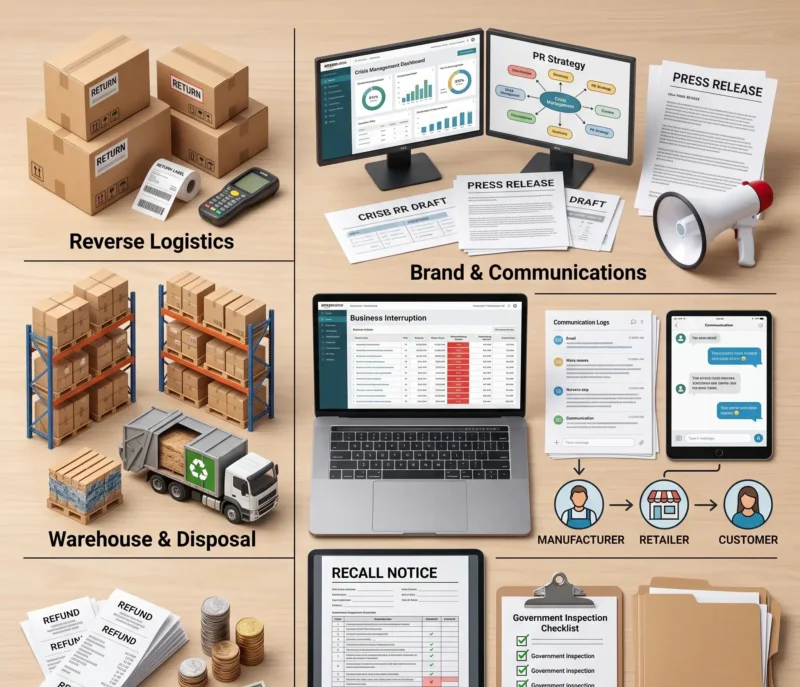
This is the layer that a standard ecommerce business insurance program almost never includes by default.
The distinction matters most at the exact moment you can least afford to learn it, which is why the next section compares the three side by side.
Product recall insurance vs. product liability vs. general liability
They are three different policies solving three different problems, and only one of them pays to pull your product. General liability covers injuries on your premises or from your operations. Product liability covers lawsuits when your product hurts someone. Product recall covers your own cost to remove the product. The trap is assuming the coverage you already carry stretches to cover all three.
Frankly, most business owners assume they’re basically the same thing with different labels. That is my read after four decades of audits, and recall exposure is where the assumption gets expensive.
Here is the clean comparison:
Coverage |
What it pays for |
Who gets paid |
Pays recall costs? |
|---|---|---|---|
|
General Liability |
Third-party bodily injury or property damage from your premises or operations |
The injured third party |
No |
|
Product Liability |
Lawsuits alleging your product caused injury or property damage |
The injured buyer |
No |
|
Product Recall |
Your first-party cost to notify, pull, destroy, replace, and recover the product |
Your own business |
Yes |
Two ownable truths fall out of this table.
First, product liability pays the injured buyer; product recall pays to pull the product. Second, the business interruption coverage on your property policy does not respond to recall-driven income loss; only recall or contingent business interruption insurance bridges that gap.
Ready to see which layers you actually hold? Book a call for a coverage review.
Does Amazon’s required insurance cover a recall? No, and here is the gap
No. Amazon requires product liability insurance, not product recall insurance, and the two do not overlap. Once your account crosses roughly $10,000 in gross proceeds in a single month, Amazon’s own seller policy requires you to carry commercial liability insurance of at least $1,000,000 per occurrence and name Amazon as an additional insured. Sellers see that requirement and assume they are covered for “product problems.” They are not covered for the recall.
Here is what that mandated policy does and does not do:
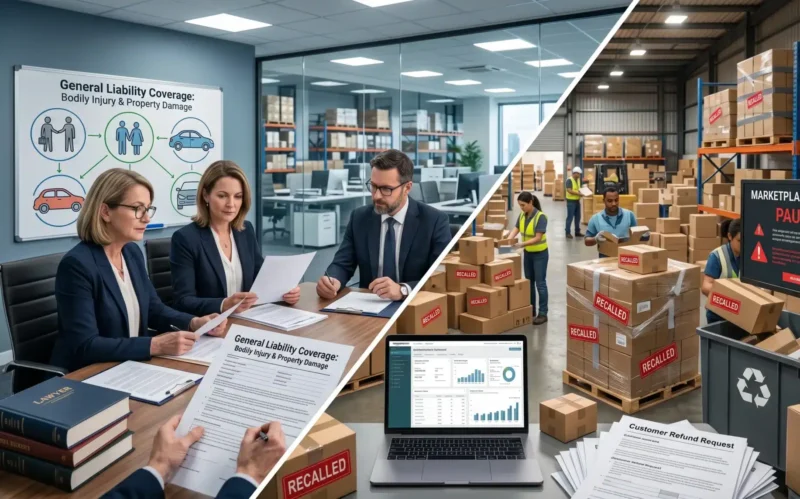
You can confirm the requirement itself inside Amazon Seller Central, and you will notice it never mentions recall response. That is the whole point.
The marketplace protects itself and any injured buyer, then leaves the first-party recall bill on your desk.
On your own Shopify store, nobody requires any insurance at all, so that same bill is yours by default. This is the single most common blind spot we see in e-commerce insurance, and closing it is a deliberate act, not a default.
Not sure whether your current policy quietly excludes recall? Contact us, and we will read the exclusions for you.
What triggers product recall coverage?
Recall coverage is triggered by evidence that a product is unsafe, defective, or contaminated, and most standalone policies do not wait for a government order to respond. A voluntary pull can trigger it just as readily as a mandated one. The nuance sellers miss is that the trigger is often a discovery, not a lawsuit, which means it can fire long before anyone is actually harmed.
Common triggers for an online seller include:
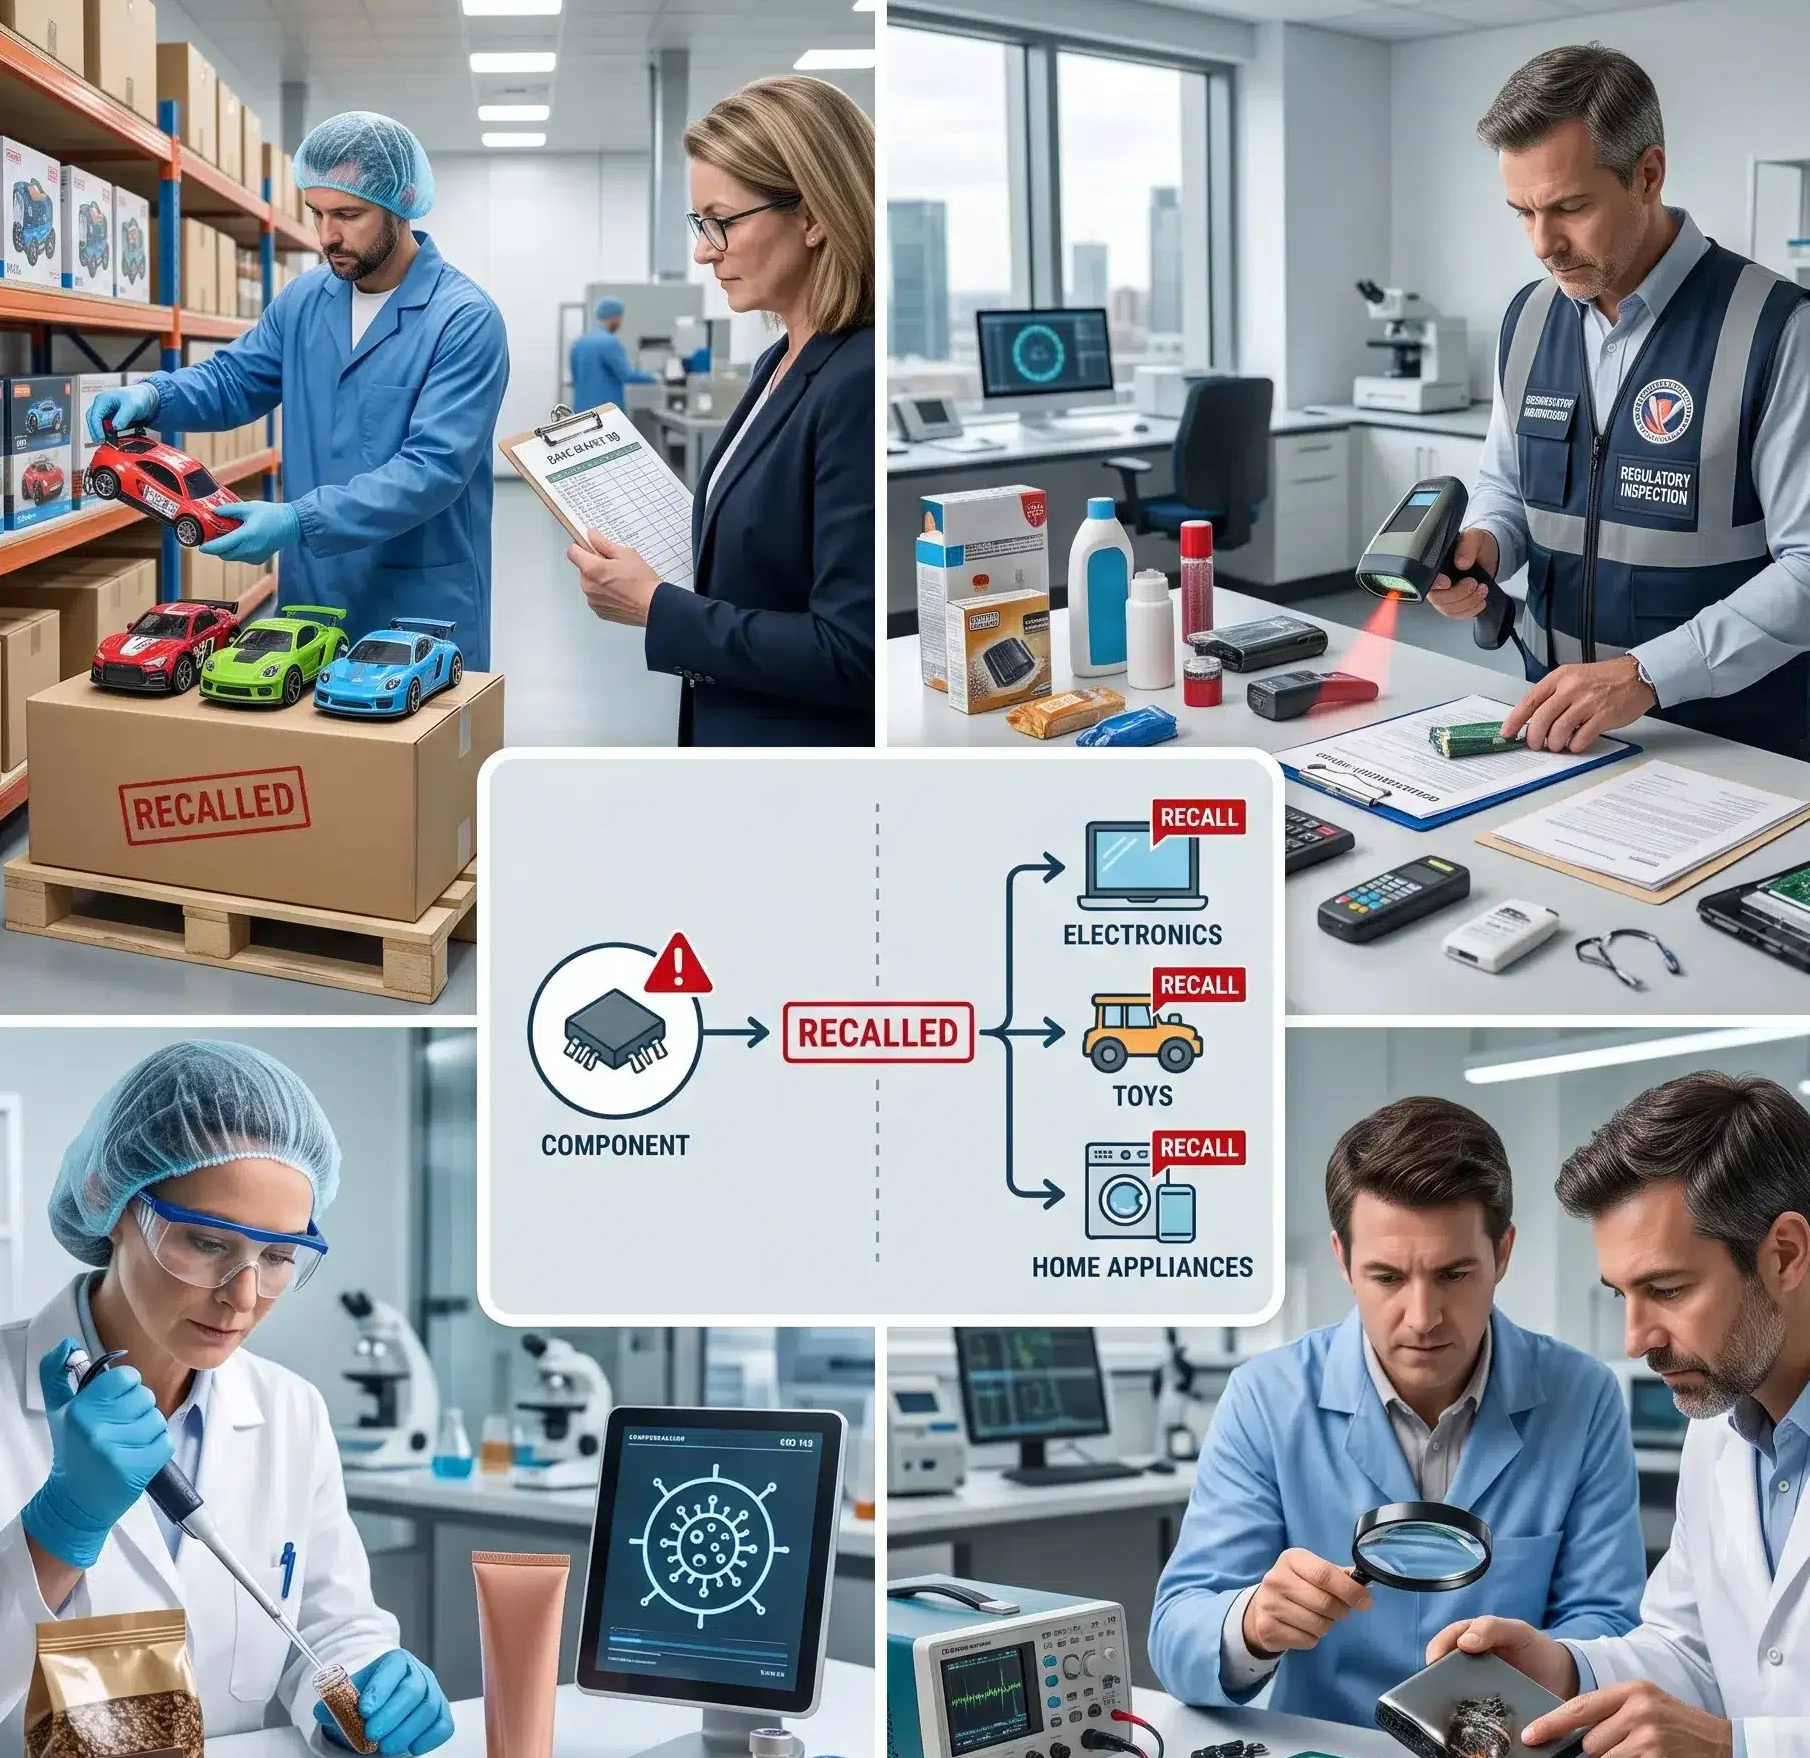
That last trigger is where a distributor or private-label seller often gets blindsided, because you inherit the safety obligation for goods you did not manufacture.
How a recall actually plays out across Amazon, Walmart, and your own store
A multichannel recall means running the same painful sequence on every platform at once, each with its own rules, timelines, and losses. The operational reality is messier than “return the bad units.” What catches sellers off guard is that the channels do not cooperate with each other, so the costs stack rather than share.
Here is the sequence, channel by channel:
Across all of them, the same steps repeat: notification, reverse logistics, inventory destruction, listing suppression, compliance documentation, and brand recovery.
Recall insurance is designed to fund each of those steps at once rather than leaving you to absorb them SKU by SKU.
What a recall really costs an online seller (illustrative scenario)
A DTC supplement brand selling across Amazon and its own Shopify store gets a supplier notice of possible contamination in one batch. The pull looks like this:
Total: well past $700,000, and not one dollar of it is paid by the product liability policy Amazon required. Recall insurance is the policy that responds.
This is exactly the scenario product recall insurance for e-commerce is built to absorb, and it is the pattern we have watched play out for product sellers again and again. and we will map it against your own channels and volumes.
Does product recall insurance cover marketplace seller fees?
Sometimes, and only when the policy wording says so. Refunds, replacement units, and destruction usually sit inside covered recall expenses. The commission and fulfillment fees a marketplace keeps on refunded orders are different, because insurers tend to treat them as lost profit rather than recall cost. That one distinction decides whether those fees come back to you.
Here is how the pieces usually sort out:
From what I’ve seen, sellers rarely ask this question before a claim, and that is exactly when the answer matters most. Ask the underwriter in writing, before you bind, how retained marketplace fees are treated. If the answer is vague, get an endorsement that names them.
Do you need standalone recall coverage for your product category?
Yes for most consumable, children’s, and battery-powered categories, and it is optional but wise for general merchandise. The higher your contamination or safety-hazard exposure, the closer standalone recall coverage moves from “nice to have” to “non-negotiable.” The wrinkle is that regulation, not just risk, can decide the answer for you.
Product category |
Primary recall trigger |
Standalone recall coverage? |
|---|---|---|
|
Supplements & nutraceuticals |
Contamination, adulteration, mislabeling |
Strongly recommended |
|
Cosmetics & personal care |
Contamination, adverse reactions, FDA reporting |
Strongly recommended |
|
Food & beverage |
Pathogens, allergens, spoilage |
Essential |
|
Toys & children’s products |
Choking and safety hazards, CPSC action |
Essential |
|
Private-label goods |
A supplier defect you inherit as the brand of record |
Strongly recommended |
|
Apparel & general merchandise |
Defect, flammability, chemical content |
Recommended |
|
Consumer electronics & batteries |
Overheating, fire, electrical hazards, CPSC action |
Strongly recommended |
Two categories deserve a special note.
If you sell supplements, contamination and mislabeling are the leading recall drivers, and these are precisely the “difficult” ingestible products many carriers hesitate to write. Private-label sellers carry a quieter risk: you become the brand of record, so a manufacturer’s mistake becomes your recall. and we will match coverage to your exact category mix.
How much recall insurance do you need? Sizing your limits
Enough to fund a full multichannel pull plus the income you lose while your top SKUs are dark, which for most serious online sellers means limits in the low millions, not $100,000. The right number is not a guess; it is a calculation off your distribution depth and category risk. The catch is that your biggest retail partners may set the floor before you do.
Size your limits against these factors:
In more than 40 years of structuring coverage for product businesses, that mismatch between the limit purchased and the loss possible is one of the fatal flaws we find most often.
My rule of thumb is direct: any online seller doing meaningful volume, and especially those under $20 million in revenue with thin reserves, should treat product recall insurance for e-commerce as core, not optional.
What product recall insurance won’t cover (exclusions to watch)
Recall insurance pays to pull and recover the product, but it will not pay injured-party claims, known pre-existing defects, or losses that belong to a different policy. Knowing the edges is what keeps a claim from getting denied. The exclusion that surprises sellers most is the one that overlaps with the coverage they thought they already had.
Typical exclusions and boundaries include:
This is where a specialist earns the fee, because the gap between two policies is invisible until a claim lands in it.
If recall coverage has never come up in your insurance conversations, treat that as the red flag it is. Contact us for a second set of eyes on your exclusions.
Are you eligible? What underwriters look at before they quote
Most online sellers can get recall coverage, but eligibility and price come down to how well you can show control over your product. Underwriters are not judging your size first. They are judging whether a defect would be caught early, traced quickly, and contained to one batch, and that changes the whole conversation.
In my experience, these five factors decide whether you get a quote and what it costs:
Small stores are not shut out of product recall insurance for e-commerce, but minimum premiums apply, so the diagnosis has to come before the quote. That is the order we follow.
How do you compare product recall insurance for online sellers?
Compare the wording, not the premium. Two policies with the same limit can respond completely differently to the same recall, because the trigger, the sublimits, and the territory decide what actually gets paid. Price is the last thing to compare, and the reason why is simple: the cheapest policy is usually the one with the narrowest trigger.
Use this checklist side by side:
Question to ask |
What a strong answer looks like |
|---|---|
|
Is it a standalone policy or a sublimit? |
Standalone recall policy with its own limit |
|
Does a voluntary recall trigger it? |
Yes, voluntary and government-mandated recalls both respond |
|
Is lost income included? |
Business interruption or lost gross profit is part of the policy |
|
Where does coverage apply? |
The territory matches every country you sell into |
|
How are marketplace fees treated? |
Named in writing, not left to interpretation |
|
Does the limit meet retailer requirements? |
Yes, with room for a multichannel pull |
|
Are brand rehabilitation costs covered? |
Yes, with a meaningful sublimit |
Comparing options for product recall insurance for e-commerce is smart, and you should do it. The trouble starts when several brokers take the same submission to the same handful of recall markets. You fill out duplicate applications, underwriters see your account more than once, and a generalist can misclassify the product, which costs you terms. One capable broker who knows which insurers actually write online sellers gives you a cleaner comparison with less work.
Why work with a specialist broker to structure recall coverage
Because recall coverage lives in the seams between three policies, and generic agents and online platforms do not build for the seams. A specialist starts from how your business actually gets hurt, then structures liability, recall, and business interruption to cover the whole event with no gap. That is what good product recall insurance for e-commerce looks like: coverage built around the event, not around a template. What you get is not a cheaper policy; it is one that pays when you need it.
Here is how The Coyle Group works with product sellers to:
The benefit is fewer applications, fewer duplicate requests, and one point of contact from submission to claim. For product businesses, a recall is the risk that quietly threatens the whole company, and it is the one most often left uninsured. You don’t need five brokers shopping your insurance. You need one capable broker making sure the right insurers compete for your business.
Book a 15-minute call, with two ways to use it:
Questions about Product Recall Insurance For E-Commerce?
Get the Right Coverage for Your Product Recall Insurance for E-Commerce
If you sell physical products online, you need coverage built for the way a recall actually hits an online seller. The gaps in most e-commerce insurance programs are not obvious. They show up when Amazon force-removes a defective batch, when a supplier’s contamination becomes your recall, or when your best-selling listing goes dark and the income stops.
Your job is to make the decision to review your coverage. Our job is to find every gap and fix it before a recall does.
Start with a conversation. We will walk you through exactly what a complete product recall insurance program looks like for your specific product line and sales channels, with no obligation and no pressure.
This article was written by the CEO of The Coyle Group, Gordon B. Coyle, CPCU, ARM, AMIM, PWCA, who has over 40 years of experience working with business owners of all sizes and industries across the US, solving their insurance challenges.
Here’s how to take the next step
Schedule Your Insurance Confidence Assessment
In our 30-minute call, you’ll discover:
Not ready for a call?
Get Free Access to Our Gated Video:
“How to Finally Feel Confident in Your Coverage. “
And discover the exact system we use to help business owners eliminate hidden coverage gaps, stop overpaying, and finally feel confident in their protection.
What Peace of Mind Looks Like
Trusted by business owners across the U.S.
The Coyle Group is 1st class! Gordon and his team are knowledgeable, responsive, and attentive to detail. Gordon is that rare breed of professional who genuinely cares for his clients and works hard to exceed their expectations. I highly recommend them.

The insurance brokerage service was truly tailored to my needs, nothing like those big brokers who steer you toward random policies that don’t fit your profile. Thank you to the team for your help.
I was working with another broker and having difficulty acquiring General Liability coverage. A colleague recommended The Coyle Group. They were able to get coverage bound in just a couple of business days and a policy issued in ten days, and with a solid carrier at a competitive premium. Truly impressive results, plus it was a pleasure working with them. I highly recommend the Coyle Group!
If any business is looking to work with an insurance brokerage firm that is not only excellent at what the firm does, but one that deeply values the needs of the clients, then The Coyle Group is the firm for you. Give them a call and see for yourself. I can assure that you will quickly agree.

Want to know more?
See related blogs

Product Liability Insurance for Importers: What You Need to Know (Video)
How to Protect Your Business From a Product Recall
The Boar’s Head Product Recall – What’s Insured?
