
Does Product Liability Insurance Cover Old Products?
The Exclusion Nobody Warns You About
Index

Gordon B. Coyle
CEO, The Coyle Group
845-474-2924
How to get started
Does product liability insurance cover old products? Usually yes, if you’re on an occurrence-form policy and coverage is in force when the injury happens, because it’s the injury date that matters, not the sale date. But a common “prior products” exclusion buried in cheaper or generalist-sold policies can quietly strip that protection away. Here’s how to check your own policy and fix it before a claim tests it.
Business owners who make, import, sell, or distribute physical products ask me some version of this question all the time, usually right after they’ve gotten a quote that made them nervous. In my experience, what I hear from business owners is some version of “almost every quote I’m getting says they won’t cover anything I sold before the policy started, even if the injury happens while I’m covered.”
That’s a real pattern, not a rumor.
Startups and smaller sellers see it constantly on cheap or online-portal policies, and it’s genuinely confusing, because most people assume “I have product liability insurance” means everything they’ve ever sold is protected forever.
It isn’t automatic, and the fine print is where that assumption falls apart.
The Coyle Group is a commercial insurance agency that handles the complex, high-value risks other agencies don’t know how to structure, where the details in the policy are the difference between a paid claim and a denied one, and this is exactly one of those details.
If you sell to wholesalers, distributors, or retailers, or you’re the one doing the distributing, the timing rules buried in your policy matter as much as the limits printed on the declarations page.
A product you sold years ago, possibly before you even bought this policy, comes back to bite you, and your carrier denies the claim.
We review the actual exclusion wording in your program, not just the declarations page, and negotiate the “prior products” exclusion out before you bind.
In my experience, almost every insurance program we review contains at least one fatal mistake, and a prior-products exclusion is one of the most common ones we find.
Book a no-obligation policy review and I’ll tell you exactly what your policy says.
What Actually Decides If an Old Product Is Covered: The Sale Date or the Injury Date?
The injury date decides it, not the sale date or the manufacture date. On a standard occurrence-form CGL policy, coverage is triggered by when someone actually gets hurt. That’s the good news. The catch: a single missing endorsement can flip that rule, and a denied claim can cost you six or seven figures, out of your own pocket.
Here’s the mechanic in plain terms:
This is the first thing I check when I audit a new client’s program, because it’s also the first thing a generalist broker skips. Over 40 years I’ve found that the owners who get burned aren’t careless, they simply never had a reason to think their policy needed a second look.
Not sure which form your policy actually uses? Book a call and we’ll pull it up together.
Occurrence vs. Claims-Made: Which One Leaves Your Old Products Exposed?
Occurrence forms generally protect old products; claims-made forms can quietly cut them off. The difference sounds technical, but it decides whether a product you sold years ago is covered today. An occurrence policy looks at the injury date. A claims-made policy looks at the claim date and your retroactive date, which means an old product can fall through a gap even while you’re actively paying premiums.
Occurrence |
Claims-Made |
|
|---|---|---|
|
What triggers coverage |
The policy active when the injury happens |
The policy active when the claim is made, subject to the retro date |
|
Are products sold before the policy covered? |
Generally yes, if the injury occurs during the policy period |
Only if the product was sold on or after the retroactive date |
|
What the retro date does |
Not applicable |
Sets a hard cutoff; anything before it is excluded, even while you’re insured |
|
What happens if you cancel or switch |
Past products stay covered by whichever occurrence policy was active when the injury happened |
You may need tail coverage, or the new carrier may not honor the old retro date |
|
Best for product sellers? |
Usually yes, it’s the safer default |
Only if you understand the retro date and manage it actively every renewal |
A few things worth flagging while you’re comparing forms:
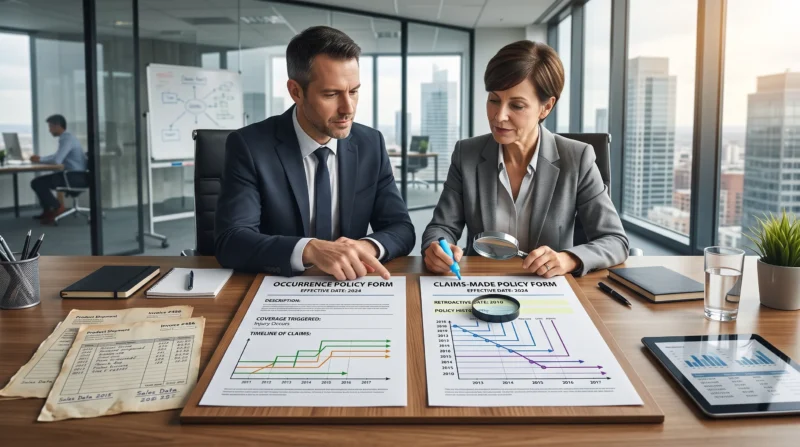
The distinction matters most at the exact moment you’d expect it to matter least: right after you’ve sold the business, discontinued a product, or moved to a new carrier and stopped paying close attention.
Still unsure whether your program is occurrence or claims-made? Reach out and send over your declarations page.
The Sneaky Exclusion That Turns Your Occurrence Policy Into a Claims-Made Policy
A “prior products” exclusion can strip occurrence protection from anything you sold before your policy started, even on a policy that otherwise looks like a normal occurrence form. This is the trap nobody names, and it’s why does product liability insurance cover old products has no flat yes answer. I call it an occurrence policy wearing a claims-made mask, because it quietly reintroduces a hidden cutoff date.
Real exclusion wording I’ve seen in the field includes language like a policy that excludes “loss incurred in respect of a covered product first placed on the market more than 3 years prior to the inception date,” or a clause excluding any claim “made prior to or existing at the inception of the policy period.”
Some policies frame it as damage that “first occurred prior to the inception date of this policy.”
The wording varies by carrier, but the effect is always the same: everything you sold before a certain date is quietly carved out, and you’d never know it unless you actually read the endorsements schedule, not just the declarations page and the limits summary.
What a Denied Product Claim Actually Costs You
A single denied product claim can run into six or seven figures once you add defense costs to a settlement, and the data backs up why insurers fight so hard over this exclusion. Litigation trends added an estimated $231.6 billion to $281.2 billion in increased liability insurance losses over the past decade, and product claims get expensive fast once lawyers get involved.
That figure comes from a joint analysis by the Casualty Actuarial Society and the Insurance Information Institute, with product liability occurrence coverage alone accounting for an estimated $4.6 billion to $4.8 billion of that increase.
The numbers on individual cases are just as sobering:
A scenario I’ve seen play out more than once
Abusiness owner buys a new policy in 2026. In 2027, they get sued over a product they made and sold back in 2023, before this policy ever existed. If that new policy carries a prior-products exclusion, the carrier denies the claim outright, and the owner is left funding defense costs and any settlement personally, because the prior policy either lapsed or never had the right form to begin with. Nobody caught it at the time, because nobody read the exclusion schedule before binding.
Reach out before you’re the business owner living out that scenario.
Who This Hits Hardest: Importers, Distributors, and Product Sellers
Anyone who puts a physical product into someone else’s hands carries this exposure, but importers, distributors, and multi-channel sellers see it most, because they’re juggling the most policy changes. Every switch of insurers, new supplier relationship, or new sales channel is another chance for a prior-products exclusion to slip into your renewal unnoticed.
Want a second set of eyes on your program as an importer or distributor?
What Happens to Your Coverage When You Discontinue a Product or Close the Business?
Closing a product line or shutting down the business doesn’t automatically protect you, and in most cases it does the opposite. An active occurrence policy only responds to injuries while it’s in force. Cancel it for any reason (closing the line, selling the business, switching carriers) and it stops responding to new claims, even if the product is still out there.
What I’ve found over 40 years is that most owners make this decision reactively, at the exact moment they’re closing up shop, instead of pricing it out while they still have options and leverage with a carrier.
How to Check Your Own Policy (and Get the Exclusion Removed)
You can check this yourself in about fifteen minutes, and it starts with the endorsements page, not the declarations page. The declarations page tells you your limits. The endorsements and exclusions schedule tells you what those limits actually apply to, and that’s exactly where a prior-products exclusion lives, quietly, in language most owners have never read.
If you’ve been with the same broker for years and have never had this conversation, it might be time to look at how to switch insurance brokers the right way, without opening a coverage gap in the transition.
Ready to have someone else read the fine print for you?.
Can a Defect You Already Knew About Void the Coverage?
Yes, a known defect can void coverage even while your policy is otherwise active, and it’s a separate issue from the prior-products exclusion entirely. Most policies carry a “prior knowledge” or known-loss exclusion, denying coverage for any defect you already knew about before buying or renewing. You can’t sit on a known problem and expect coverage to apply retroactively once a claim lands.
Full disclosure at renewal protects you here.
Silence does not, and it tends to surface at the worst possible moment, in the middle of a claim investigation.
Why I Built The Coyle Group to Catch Exactly This
I’ve spent over 40 years helping business owners navigate the complex world of commercial insurance, and prior-products exclusions are exactly the kind of detail I built The Coyle Group to catch.
In my experience, this isn’t a rare or obscure clause. It shows up constantly in the programs I audit, especially for businesses that bought on price or haven’t had a real broker relationship in years. I don’t win business by competing on premium alone. I win it by finding the gap before it costs a client a claim.
If you make, import, sell, or distribute physical products, I’d rather have one honest conversation about what’s actually in your policy than let you find out the hard way after a claim gets denied.
That’s the whole reason questions like does product liability insurance cover old products deserve a specific answer, not a generic one.
Ready to Check Your Own Policy?
You don’t need to read every page of your policy to find out if you’re exposed. and I’ll walk through your endorsements with you directly, or Reach out if you’d rather send the policy over first. Either way, it costs you nothing to find out before a claim forces the question for you.
Questions about Does Product Liability Insurance Cover Old Products?
Get the Right Coverage for Every Product You’ve Already Sold
We read the exclusions, not just the declarations. In more than 40 years of reviewing product liability programs, we find a prior-products exclusion is one of the most common gaps buried in a policy, and we catch it before a claim does, not after.
We are advocates, not order-takers. We negotiate prior-products exclusions out directly with carriers, using relationships a generalist broker or an online portal simply doesn’t have.
We put continuity ahead of price. We build your program so coverage for what you’ve already sold never quietly lapses when you switch carriers, discontinue a product, or close a line.
95+
Years of Family Legacy in Insurance
40+
Years Personal Experience
95%
Client Retention Rate
600+
Educational Videos

This article was written by the CEO of The Coyle Group, Gordon B. Coyle, CPCU, ARM, AMIM, PWCA, who has over 40 years of experience working with business owners of all sizes and industries across the US, solving their insurance challenges.
Here’s how to take the next step
Schedule Your Insurance Confidence Assessment
In our 30-minute call, you’ll discover:
Not ready for a call?
Get Free Access to Our Gated Video:
“How to Finally Feel Confident in Your Coverage. “
And discover the exact system we use to help business owners eliminate hidden coverage gaps, stop overpaying, and finally feel confident in their protection.
What Peace of Mind Looks Like
Trusted by business owners across the U.S.
The Coyle Group is 1st class! Gordon and his team are knowledgeable, responsive, and attentive to detail. Gordon is that rare breed of professional who genuinely cares for his clients and works hard to exceed their expectations. I highly recommend them.


The insurance brokerage service was truly tailored to my needs, nothing like those big brokers who steer you toward random policies that don’t fit your profile. Thank you to the team for your help.

I was working with another broker and having difficulty acquiring General Liability coverage. A colleague recommended The Coyle Group. They were able to get coverage bound in just a couple of business days and a policy issued in ten days, and with a solid carrier at a competitive premium. Truly impressive results, plus it was a pleasure working with them. I highly recommend the Coyle Group!

If any business is looking to work with an insurance brokerage firm that is not only excellent at what the firm does, but one that deeply values the needs of the clients, then The Coyle Group is the firm for you. Give them a call and see for yourself. I can assure that you will quickly agree.

Want to know more?
See related blogs

The Crowdstrike Debacle and Cyber Insurance
Third Party Employment Practices Liability Insurance. Protect Your Business

Are You Overpaying or Underinsured on Your Business Insurance?
