
How Often Should Your Insurance Account Manager Change?
What’s Normal vs. a Red Flag
Index

Gordon B. Coyle
CEO, The Coyle Group
845-474-2924
How to get started
Maybe it feels like every few months, another email lands in your inbox announcing a new account manager. Maybe it happened once, years in, and you’re just not sure if that’s normal or the first crack in something bigger.
TL;DR. Executive summary
There’s no fixed rotation schedule.
Real industry data puts agency and service-staff turnover at roughly 15% to 16% a year, and the average insurance CSR stays two to three years in a seat, meaning most accounts should expect a change roughly every two and a half years.
Your account manager changed, again, and nobody explained why or what happens next.
I treat every account handoff on my team as a documented transition, not a forwarded email, because your renewal dates and coverage gaps don’t pause while a new person gets up to speed.
A 95% client retention rate, built on institutional knowledge that survives staff changes instead of walking out the door with them.
Book a 30-minute call and I’ll tell you honestly whether your current setup is normal staffing or a real problem.
The Coyle Group is a commercial insurance agency for business owners who’ve outgrown one-size-fits-all coverage and need a specialist who understands the nuances.
Is It Normal for Your Insurance Account Manager to Change?
Yes, and more often than most business owners expect, though “how often” turns out to be the wrong question to obsess over on its own. Industry data puts overall agency and brokerage employee turnover at 16.4% in 2024, easing to 15.1% in 2025, per MarshBerry’s Insurance Agency and Brokerage Compensation Report, lower than the 20% to 25% typical of broader financial services. Here’s the number that actually answers the question.
Covu’s 2026 analysis puts the average tenure of an insurance CSR at two to three years in a given agency role, which means a well-run agency should plan for, and warn you about, a turnover event roughly every two and a half years per account manager seat. How often does your insurance account manager change? Based on that benchmark, somewhere in that range is statistically normal, not a red flag by itself.
Benchmark |
Figure |
Source |
|---|---|---|
|
Overall agency/brokerage employee turnover |
16.4% (2024) → 15.1% (2025) |
MarshBerry |
|
Average insurance CSR tenure per role |
2 to 3 years |
Covu |
|
Recommended CSR turnover ceiling |
Below 15% annually |
Sonant |
|
Service staff leaving within 3 years |
52% |
Insurance Business America / TeamIQ |
|
Industry-wide personnel movement, 2025 vs. 2024 |
16% lower |
Insurance Insider Talent Tracker |
In my experience, business owners rarely get upset about a personnel change itself. They get upset about being the last to know, having to re-explain their business from scratch, or discovering a coverage gap because nobody owned the file during the gap between people.
Book a Call if you want a straight read on whether your current account manager situation is normal or a warning sign.
What’s the Difference Between a Broker, an Agent, and an Account Manager?
An agent or broker is usually the person who sold you the policy and owns the overall relationship, while an account manager, sometimes called a CSR, handles the day-to-day servicing: certificates, endorsements, claims coordination, and renewal prep. Knowing which is which changes who you should actually be asking when something changes.
In practice, the line blurs at smaller and mid-market agencies, where one person may wear both hats early on and then hand off the servicing role as your account grows.
That’s not a downgrade.
Why Insurance Account Managers Actually Leave
Most of the time, it isn’t about you, and it usually isn’t about incompetence either. It’s an industry-wide workload problem that’s been building for years, and understanding it changes how you read the next email announcing a new contact.
Liberty Mutual’s 2025 Independent Agents at Work Study found that 65% of frontline agency staff often feel stressed, 57% feel mentally or physically exhausted, and 51% report outright burnout. Burned-out staff are more than twice as likely to be job hunting, and 60% say they plan to change jobs within the next 12 months. Separate 2025-2026 industry commentary found 87% of frontline brokerage staff say their workload increased over the past year, a pattern echoed almost word for word by agency professionals themselves.
Another reported losing a staggering 75% of their training cohort within the first year.
None of this excuses a bad transition.
By contrast, the broader “finance and insurance” sector actually posts one of the lower monthly quits rates of any major U.S. industry, around 1.1% to 1.4%, according to the Bureau of Labor Statistics.
That gap between the calm macro number and the very real burnout data at the agency level tells you something important: insurance isn’t inherently a high-churn industry.
The churn is concentrated in specific roles at specific agencies that haven’t fixed their workload problem, which is exactly why the agency you choose matters more than the industry average.
When an Account–Manager Change Is Normal vs. a Warning Sign
One change is a staffing event. A pattern of changes with no handoff plan is a signal about the agency itself, and the difference matters because it determines whether you need a conversation or a new broker entirely.
Normal reasons for a change:
Warning signs worth paying attention to:
Quick reference |
What it usually means |
|---|---|
|
One change, with notice and a documented handoff |
Normal staffing, not a red flag |
|
Multiple changes, no advance notice each time |
Agency-level workload or retention problem |
|
New contact already knows your file on day one |
A real transition process exists |
|
You have to re-explain your business from scratch |
No transition process, or a rushed one |
|
Deadlines or certificates slip during the change |
The gap is being covered by no one |
Frequent changes only become a real problem when they come paired with these gaps.
A thorough guide should never invent a rigid “every X years” rule, because the honest answer is that continuity of service matters more than the calendar.
Contact Us if you’re seeing more than one of these warning signs right now.
What a Proper Account–Manager Handoff Should Look Like
A good handoff means you’re transferred, not abandoned, and it should never depend on your new contact learning your account by trial and error at your expense. There’s a specific, checkable list of what a real transition includes, and most business owners have never seen it laid out, which is exactly why it’s easy for a rushed agency to skip half of it without you noticing until something slips.
A properly managed transition includes:
How this looks in practice
When an account manager transition happens on my team, the incoming contact reviews the client’s full file, including current limits, open items, and renewal timing, before the introduction call ever happens. I make sure the client is told who owns their account during the gap, not left to guess. That’s the difference between a broker who is managing your program and one who is simply processing whatever lands on a desk.
If your last transition didn’t include most of this list, that’s useful information, not just a complaint.
It tells you whether the problem was one employee leaving or whether the agency doesn’t actually have a transition process at all.
How Many Account–Manager Changes Is Too Many?
There’s no single number, but the pattern is more telling than the count. One clean change with a documented handoff is not a problem. Multiple changes with no named backup, no written transition plan, and declining service each time is a pattern worth escalating.
Ask yourself three questions.
Book a Call and walk me through what’s happened. I’ll give you a direct read on whether it’s a pattern worth acting on.
Should You Switch Insurance Brokers Over Account–Manager Turnover?
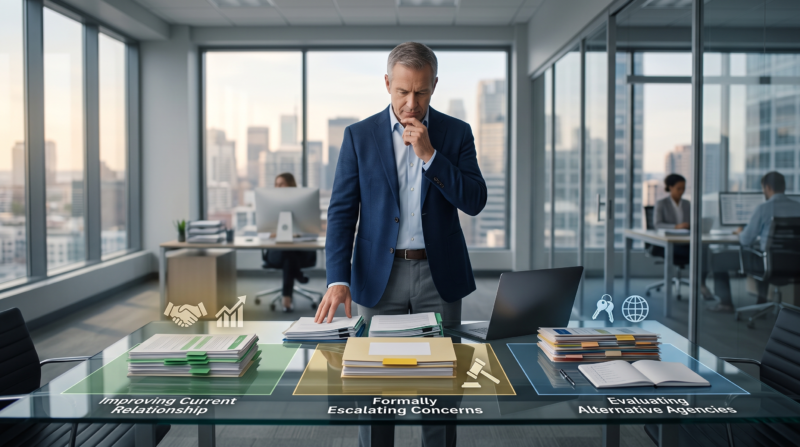
Not automatically, and not over one well-handled change. But repeated turnover paired with the warning signs above is exactly the kind of evidence that should factor into that decision, separate from whether your broker’s expertise still fits your business.
If your account manager keeps changing but the agency clearly has a real transition process, that’s a firm worth staying with.
If the turnover comes paired with missed renewals, coverage gaps nobody caught, or an agency that can’t explain what happened, that’s the same pattern I’ve written about when it comes to outgrowing your broker entirely, and it may be time to have that harder conversation.
If you do conclude it’s time to make a change, switching brokers is a more straightforward process than most business owners expect, and it doesn’t require waiting until your renewal date to start the conversation.
A short version of that decision, side by side:
How to Protect Your Business From Account–Manager Turnover
Whatever happens with any single account manager, your business shouldn’t depend on one person’s memory, because that’s a single point of failure you don’t need to accept. A few habits protect you regardless of who’s assigned to your account, and they take far less ongoing effort than most business owners assume once they’re actually in place.
Build resilience into your own insurance program:
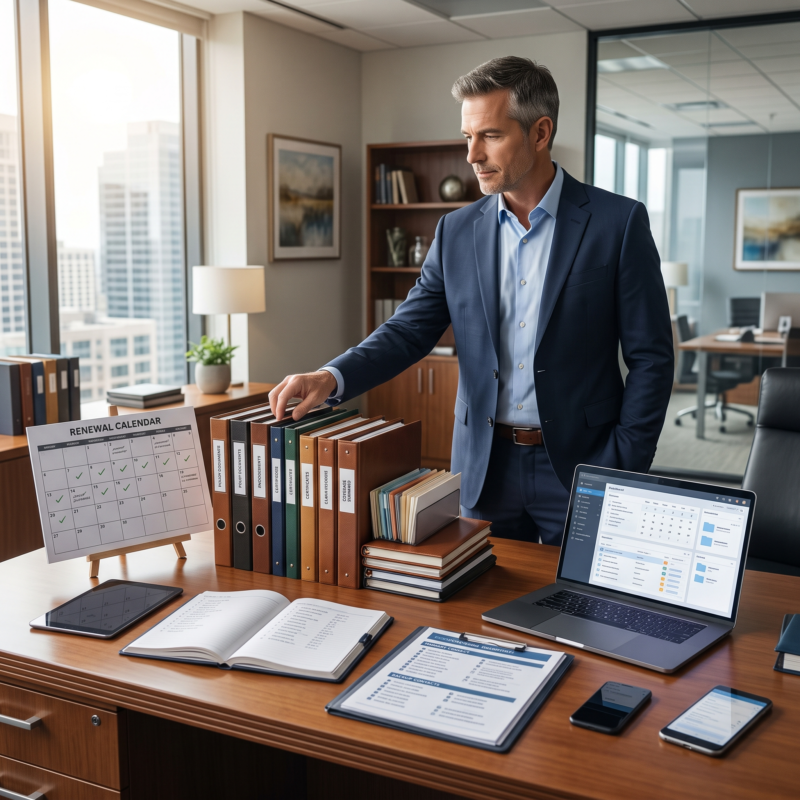
From what I’ve seen, the businesses that never notice a personnel change are the ones who already treat their insurance program as something they own and track, not something they hand off entirely and forget about.
That doesn’t mean doing your broker’s job for them.
It means having enough of your own record that a staff change at the agency is an inconvenience, not a crisis.
If not, that’s not a knock on you.
It’s a sign your program has been living entirely in someone else’s inbox, and it’s worth fixing before a staffing change forces the issue.
Contact Us for a straightforward second opinion on whether your program is actually being managed or just being processed.
What a Broker Built for Continuity Actually Does
Frankly, most agencies aren’t built to survive staff turnover gracefully, because their systems live in one person’s head instead of in a documented process, and that’s the actual gap this whole question comes down to. The fix isn’t hiring people who never leave. It’s building a program that doesn’t fall apart when someone does, which is a standard you can actually ask any agency, including this one, to explain in specific terms rather than take on faith.
If the answer is no, the account isn’t being managed, it’s being remembered by one employee, and that’s a fragile way to run a mid-market insurance program.
That standard is a big part of why The Coyle Group maintains a 95% client retention rate. It isn’t because turnover never happens to my team. It’s because when it does, the file, the history, and the relationship survive the transition instead of walking out the door with the person who’s leaving.
That’s not a special favor reserved for the largest accounts.
It’s the baseline for how I believe an insurance program should be run, whether you’ve been with me for one renewal or fifteen.
According to the Insurance Information Institute, finding the right insurance professional means working with someone who understands your business well enough to advise you confidently, not just process paperwork, a standard that should survive any single staff change regardless of the broader labor-market turnover data discussed above.
The Coyle Second Opinion
9 out of 10 business insurance policies we review have a gap that would sink a claim
Yours might be one of them, and the only time you find out is when you file a claim and it gets denied. Send us your policy for an independent, confidential read: what’s covered, what’s missing, what you’re overpaying for. We never contact your broker or shop the market. Flat $2,500, refunded in full if you don’t get real value.


The team that reads your policy, line by line.
Questions about How Often Does Your Insurance Account Manager Change?
Get the Right Coverage for Your Commercial Insurance Program
The risk in an unmanaged account transition isn’t obvious until it costs you. It shows up when a renewal deadline slips because nobody owned your file during a handoff, when a certificate request sits unanswered because your new contact doesn’t know your account yet, or when a change you mentioned months ago never made it into your policy.
Your job is to notice when something feels off. Our job is to make sure a personnel change never becomes a coverage gap.
Start with a conversation. We will walk you through exactly how your account is managed, who owns it, and what happens the next time your contact changes, with no obligation and no pressure.

This article was written by the CEO of The Coyle Group, Gordon B. Coyle, CPCU, ARM, AMIM, PWCA, who has over 40 years of experience working with business owners of all sizes and industries across the US, solving their insurance challenges.
Here’s how to take the next step
Schedule Your Insurance Confidence Assessment
In our 30-minute call, you’ll discover:
Not ready for a call?
Get Free Access to Our Gated Video:
“How to Finally Feel Confident in Your Coverage. “
And discover the exact system we use to help business owners eliminate hidden coverage gaps, stop overpaying, and finally feel confident in their protection.
What Peace of Mind Looks Like
Trusted by business owners across the U.S.
The Coyle Group is 1st class! Gordon and his team are knowledgeable, responsive, and attentive to detail. Gordon is that rare breed of professional who genuinely cares for his clients and works hard to exceed their expectations. I highly recommend them.

The insurance brokerage service was truly tailored to my needs, nothing like those big brokers who steer you toward random policies that don’t fit your profile. Thank you to the team for your help.

I was working with another broker and having difficulty acquiring General Liability coverage. A colleague recommended The Coyle Group. They were able to get coverage bound in just a couple of business days and a policy issued in ten days, and with a solid carrier at a competitive premium. Truly impressive results, plus it was a pleasure working with them. I highly recommend the Coyle Group!

If any business is looking to work with an insurance brokerage firm that is not only excellent at what the firm does, but one that deeply values the needs of the clients, then The Coyle Group is the firm for you. Give them a call and see for yourself. I can assure that you will quickly agree.

Want to know more?
See related blogs

The Crowdstrike Debacle and Cyber Insurance
Third Party Employment Practices Liability Insurance. Protect Your Business

Are You Overpaying or Underinsured on Your Business Insurance?
